Do you keep your gold assets in bank locker? You are probably paying some fees every year for your lockers.

Instead, what if you could get a locker for free?

What if I said banks would pay you to keep your gold assets safe?

Time for a thread. 👇👇👇

1/ The major issue with having gold in bank lockers is

- You pay hefty fees on an annual basis to the bank.
- The lockers aren't insured
- There's no real safety/security in case of theft or an unfortunate event.

Is there a work around?

Yes.

Enter "Gold Monetisation Scheme".
2/ GOI introduced the Gold Monetisation Scheme in 2015. The main objective was to cut down India's gold imports.

How it works:

You deposit your gold in bank.
They keep it safe for a fixed number of years.
You get it back as physical gold or cash on maturity.
3/ What should you do to be eligible?

You should take the gold you want to deposit to a Collection and Purity Testing Centre (CPTC). GOI has established over 300 CPTC's across India.

They will take your gold, evaluate its purity, and provide a receipt for the gold quantity.
4/ You take the receipt to your bank.

Create a gold monetisation scheme account in your bank.

Give them the receipt provided by PTC.

Your bank will then convert that receipt to a scheme certificate as part of your GMS account.
5/ The interest rates are as follows:

5-7 years - 2.25% per annum
12-15 years - 2.5% per annum

Tax Benefits:

No capital gains tax on the profits made through this scheme.

Capital gains are also exempt from wealth tax and income tax.
6/ What all can you deposit?

You can deposit Gold bars, coins, even old jewellery.

What can you not deposit?

You can't deposit Gold jewellery encrusted with gemstones.
7/ What's the catch?

You won't get your gold back in its original form.

Upon maturity, you'll get fresh gold coin/bars or cash.

Once you deposit your jewellery/bar/coin, banks send them to Mineral Trading Corporation for minting gold coins, or sell it to jewellers.
8/ Short term deposits do not calculate interest in the form of cash. They give you interest in gold in grams.

Ex: If the interest is 0.5% per annum, you get 1 gram on 200 grams deposited, at the end of the year.
9/ Medium and long term deposits calculate interest in Rupees, based on the Gold value whenever you deposited.

If you deposited 200g at a value of 600k, and the interest rate is 2.5%, you'll get 15000 rupees as interest in a year.

This is of course tax exempt.
10/ 2.25-2.5% interest rate on Gold is on par with the SGB scheme provided by the RBI.

Also, the option to encash the gold on maturity is also attractive in case you want cash instead of physical gold once the scheme matures.
11/ Is there a cap on how much you can deposit? Yes and No.

Minimum deposit : 30 grams
Maximum deposit : Unlimited.
12/ Details of GMS in few bank websites:

SBI : https://t.co/uDmrJOM07K

ICICI : https://t.co/niB8oodCmu

HDFC : https://t.co/B67Re4iJkg

Contact your bank for more details on this.

More from Shravan Venkataraman 🔥🚀💰

Have you ever had 4-5 profitable trades in a row, and you bet all your profits on your next trade feeling "in the zone" only to lose it all?

That's called as "hot-hand fallacy" bias.

I ran a poll recently to outline two classic biases we have as humans.

Thread below 👇👇


1/ *Hot-Hand Fallacy* first had its origin in the game of basketball.

If a player shoots few baskets in a row, people generally predict that the next shot will also be a basket.

This is ignoring the fact that each shot is independent of the ones that came prior.

2/ In this poll, 41.1% people voted that the batsman who hit 4 sixes in a row, will hit a sixer in the 5th ball also.

This is classic hot-hand fallacy.

Each ball's outcome is independent.

The probability is not 50% FYI (number of outcomes is not 2).

These 148 people who voted that the next ball will also be a sixer, did so because they believe that the batsman is on a hot streak, and that his streak would continue.

This is an emotional bias and is usually attached to human performance related events only.

3/ 45.3% (162) people voted that the 5th ball would be a dot ball, meaning the batsman wouldn't score anything.

These people displayed the classic "negative-recency" bias, which is also called the "Gambler's Fallacy".
In today's round up, I have some amazing threads, resources, and plenty of solid advice for business, finance, career from twitter.

Here's the roundup of 17 of the best and the most useful threads, tweets, and resources I found last week. 🧵

1/ How to find spreadsheets on any topic in the


2/ A thread by @wes_kao on making your customers hungry and excited to buy from


3/ Life brings you a lot of afflictions. But if you look around, there's a lot of beauty around you. Most often, drowning in the afflictions, we can't recognise or appreciate the beauty.

@wdmorrisjr wrote a damn good thread on finding beauty around us.


4/ This one is for all the job goers and job seekers.

@SahilBloom who recently hit 500k followers and has several accomplishments to his belt (career wise) wrote this thread on standing out in a hiring

More from Finance

Last week Hizbollah's finance institution Al Qard el Hasan was hacked by Spiderz. A group of people took that Data and tried to make sense out of it. Below are the findings

https://t.co/eGLqvb28o5


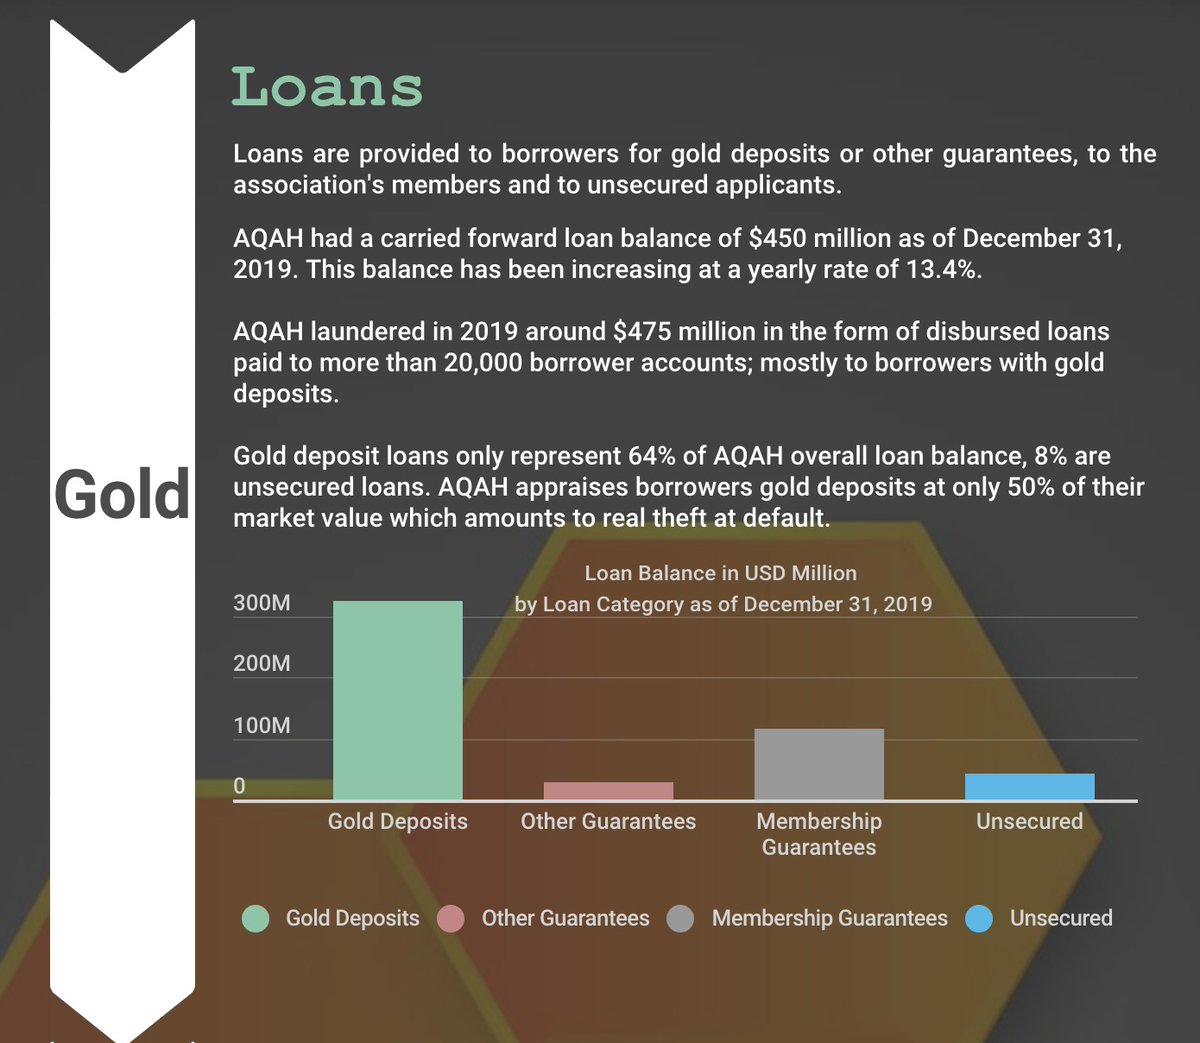
Loans are provided to borrowers for gold deposits or other guarantees, to the association's members and to unsecured applicants.

AQAH had a carried forward loan balance of $450 million as of December 31, 2019. This balance has been increasing at a yearly rate of 13.4%.


AQAH laundered around $475 million in 2019 in the form of disbursed loans paid to more than 20,000 borrower accounts; mostly to borrowers with gold deposits.

Deposits accounts have been offered to 307,000 members of the association, 83,000 contributors as well as to 600 companies. AQAH closed 2019 with an overall depositors accounts balance of around $500 million.

You May Also Like

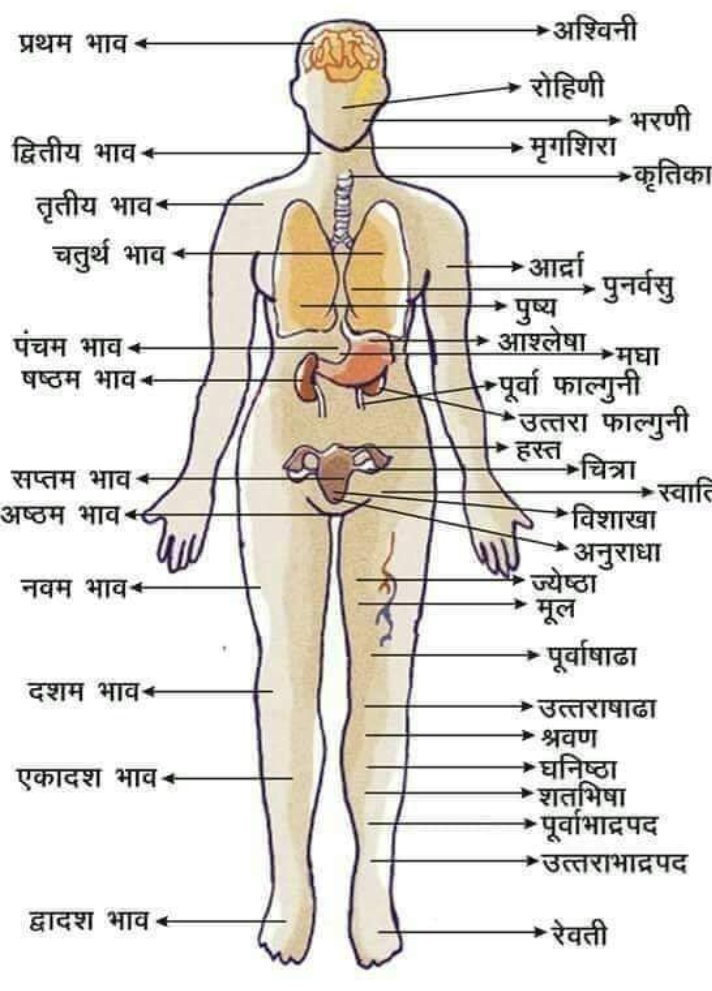
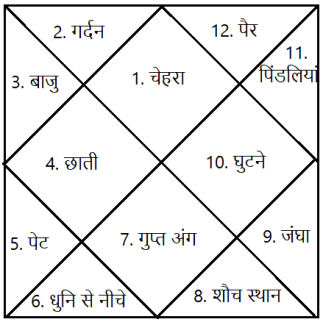
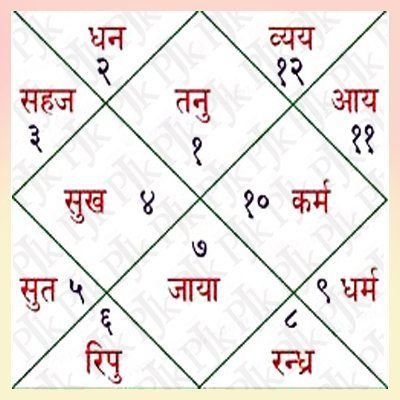
कुंडली में 12 भाव होते हैं। कैसे ज्योतिष द्वारा रोग के आंकलन करते समय कुंडली के विभिन्न भावों से गणना करते हैं आज इस पर चर्चा करेंगे।
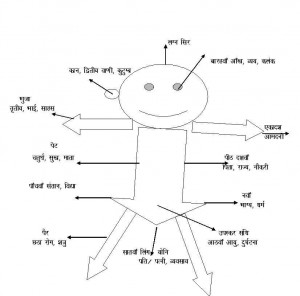
कुण्डली को कालपुरुष की संज्ञा देकर इसमें शरीर के अंगों को स्थापित कर उनसे रोग, रोगेश, रोग को बढ़ाने घटाने वाले ग्रह


रोग की स्थिति में उत्प्रेरक का कार्य करने वाले ग्रह, आयुर्वेदिक/ऐलोपैथी/होमियोपैथी में से कौन कारगर होगा इसका आँकलन, रक्त विकार, रक्त और आपरेशन की स्थिति, कौन सा आंतरिक या बाहरी अंग प्रभावित होगा इत्यादि गणना करने में कुंडली का प्रयोग किया जाता है।


मेडिकल ज्योतिष में आज के समय में Dr. K. S. Charak का नाम निर्विवाद रूप से प्रथम स्थान रखता है। उनकी लिखी कई पुस्तकें आज इस क्षेत्र में नए ज्योतिषों का मार्गदर्शन कर रही हैं।
प्रथम भाव -
इस भाव से हम व्यक्ति की रोगप्रतिरोधक क्षमता, सिर, मष्तिस्क का विचार करते हैं।


द्वितीय भाव-
दाहिना नेत्र, मुख, वाणी, नाक, गर्दन व गले के ऊपरी भाग का विचार होता है।
तृतीय भाव-
अस्थि, गला,कान, हाथ, कंधे व छाती के आंतरिक अंगों का शुरुआती भाग इत्यादि।

चतुर्थ भाव- छाती व इसके आंतरिक अंग, जातक की मानसिक स्थिति/प्रकृति, स्तन आदि की गणना की जाती है


पंचम भाव-
जातक की बुद्धि व उसकी तीव्रता,पीठ, पसलियां,पेट, हृदय की स्थिति आंकलन में प्रयोग होता है।

षष्ठ भाव-
रोग भाव कहा जाता है। कुंडली मे इसके तत्कालिक भाव स्वामी, कालपुरुष कुंडली के स्वामी, दृष्टि संबंध, रोगेश की स्थिति, रोगेश के नक्षत्र औऱ रोगेश व भाव की डिग्री इत्यादि।