THREAD - (Short term Options)
Many of the messages I get regarding options are referencing outside the money (OTM) calls w/ expirations a week or two out (or less)
It's no wonder these traders are often very concerned (even frantic) about the outcome of their trades.
a.k.a. Long term options typically w/ an expiration of longer than a year)
While playing OTM weekly options has the potential for huge returns, & will undoubtedly get your adrenaline pumping, it's also an easy way to lose your💰
Each trade should be a *very* small percentage of your account, and you should assume that every trade you make is going to zero.
You can still make massive returns on options that have expirations that are 2+ months, even 2+ years out without taking on so much immediate risk.
Once you take the time to fully understand the power of compounding, you'll be much less likely to want to trade vehicles with extremely high risk.
When I started placing more focus on consistency, protecting my capital, and compounding my money instead of hitting home runs, my account grew exponentially faster 📈
More from Economy


The International Monetary Fund (IMF) is analyzing damage due to COVID and projecting further severe consequences if current policies persist. They state “despite involving short term economic costs, lockdowns may lead to faster economic recovery by containing the virus”
1/
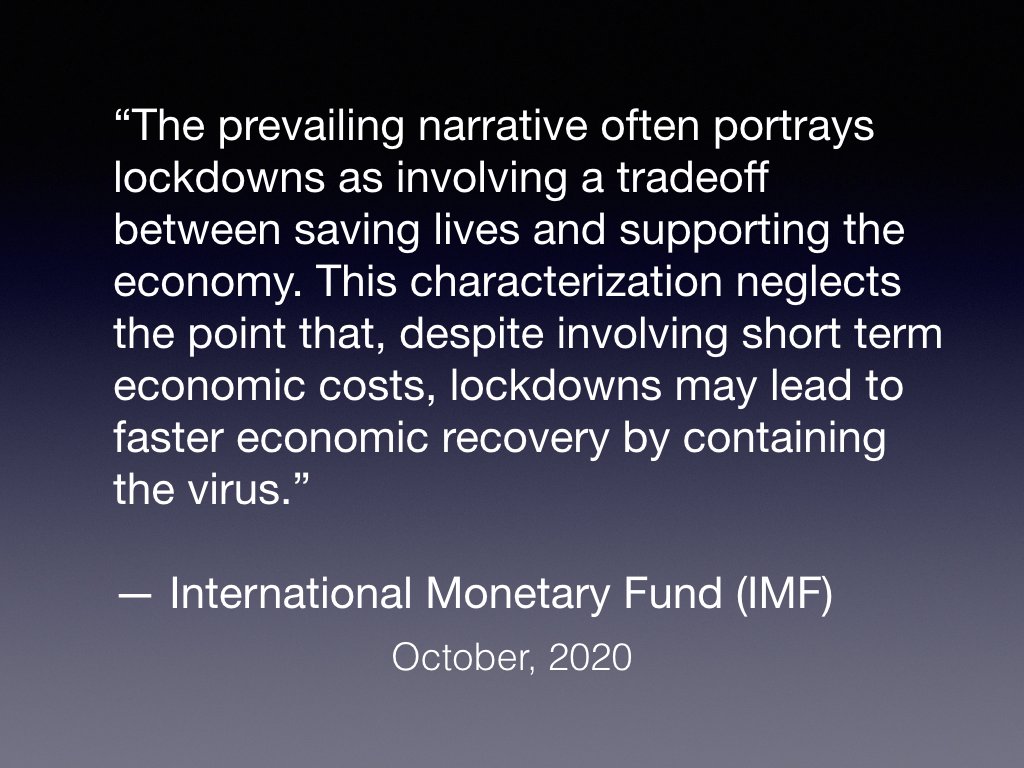
Note: This report doesn’t do a dynamic analysis that makes things much clearer, but it does a thoughtful statistical analysis based upon increasingly available data.
https://t.co/5Xmt8y7lCL
A few more quotes:
2/
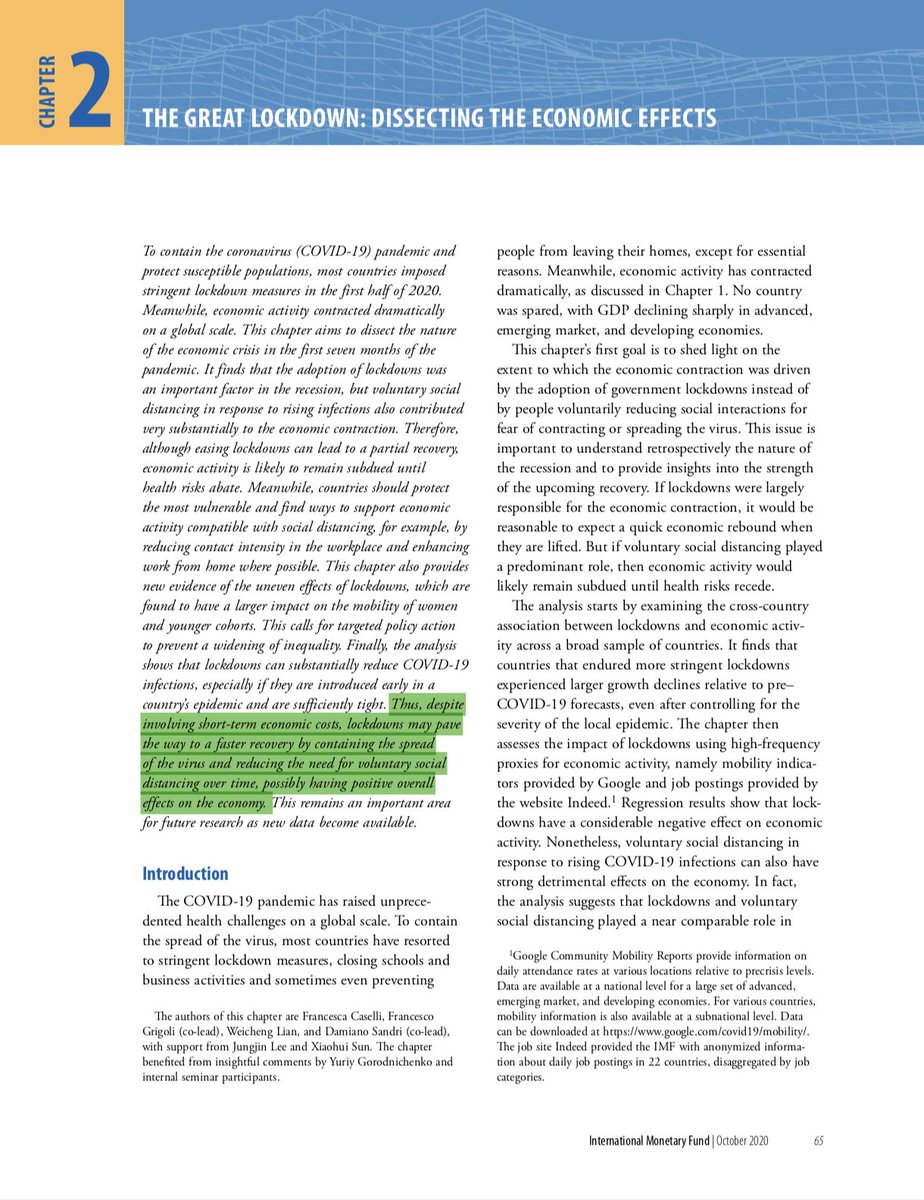
“The analysis also finds that lockdowns are powerful instruments to reduce infections, especially when they are introduced early in a country’s epidemic and when they are sufficiently stringent.”
3/
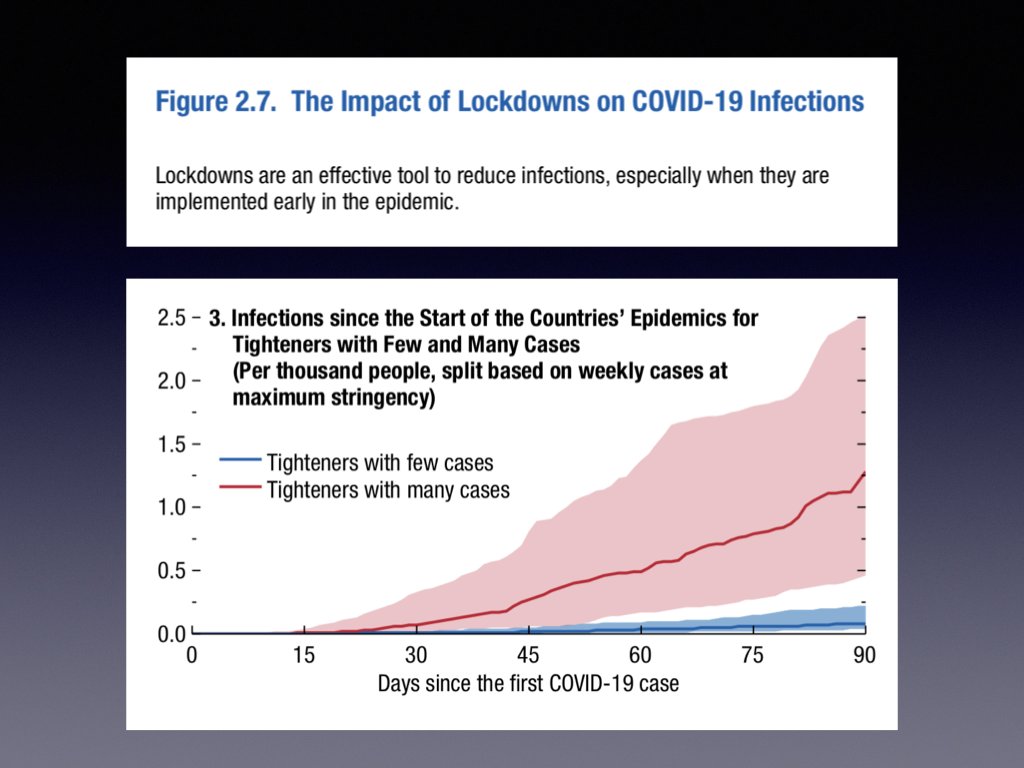
“lockdowns become progressively more effective in reducing COVID-19 cases when they become sufficiently stringent. Mild lockdowns appear instead ineffective at curbing infections.”
4/
“The results suggest that to achieve a given reduction in infections, policymakers may want to opt for stringent lockdowns over a shorter period rather than prolonged mild lockdowns...
5/
1/
Note: This report doesn’t do a dynamic analysis that makes things much clearer, but it does a thoughtful statistical analysis based upon increasingly available data.
https://t.co/5Xmt8y7lCL
A few more quotes:
2/
“The analysis also finds that lockdowns are powerful instruments to reduce infections, especially when they are introduced early in a country’s epidemic and when they are sufficiently stringent.”
3/
“lockdowns become progressively more effective in reducing COVID-19 cases when they become sufficiently stringent. Mild lockdowns appear instead ineffective at curbing infections.”
4/
“The results suggest that to achieve a given reduction in infections, policymakers may want to opt for stringent lockdowns over a shorter period rather than prolonged mild lockdowns...
5/


The argument for deficits & debt raising interest rates in the US is not increased credit risk, it is that interest rates are a function of economic fundamentals, flows & policy. Deficits/debt change those.
I can't tell if I'm agreeing or disagreeing with @jc_econ.
Increasing government spending or reducing taxes increases demand (or reduces saving). This raises the price of loanable funds or the interest rate.
In a dynamic context, more demand means a stronger economy, the central bank raises interest rates sooner, and long rates rise.
(As an aside, we are not close to the United States needing to worry about credit risk and the risks are more overstated than understated in most other advanced economies too. But credit risk is not always & everywhere irrelevant, just look at the UK in 1976 or Canada in 1994.)
Interest rates have fallen over the last 20 yrs while debt has risen. This does not necessarily mean that debt rising causes interest rates to fall. It could also mean that other things have happened at he same time that pushed down interest rates more than debt pushed them up.
The suspects for these "other things" include slower productivity growth, slower popln growth, higher inequality, less investment, etc. All of which either increase the supply of saving or reduce the demand for investment, reducing the equilibrium interest rate.
I can't tell if I'm agreeing or disagreeing with @jc_econ.
There is no relationship b/w deficits & interest rates in the US & many other advanced economies. Centuries of dynamic institution building underpin our reserve currency status that allows rates to be a function of economic fundamentals, flows & policy not credit risk 1/3
— Dr. Julia Coronado (@jc_econ) January 26, 2021
Increasing government spending or reducing taxes increases demand (or reduces saving). This raises the price of loanable funds or the interest rate.
In a dynamic context, more demand means a stronger economy, the central bank raises interest rates sooner, and long rates rise.
(As an aside, we are not close to the United States needing to worry about credit risk and the risks are more overstated than understated in most other advanced economies too. But credit risk is not always & everywhere irrelevant, just look at the UK in 1976 or Canada in 1994.)
Interest rates have fallen over the last 20 yrs while debt has risen. This does not necessarily mean that debt rising causes interest rates to fall. It could also mean that other things have happened at he same time that pushed down interest rates more than debt pushed them up.
The suspects for these "other things" include slower productivity growth, slower popln growth, higher inequality, less investment, etc. All of which either increase the supply of saving or reduce the demand for investment, reducing the equilibrium interest rate.
You May Also Like


1/OK, data mystery time.
This New York Times feature shows China with a Gini Index of less than 30, which would make it more equal than Canada, France, or the Netherlands. https://t.co/g3Sv6DZTDE
That's weird. Income inequality in China is legendary.
Let's check this number.
2/The New York Times cites the World Bank's recent report, "Fair Progress? Economic Mobility across Generations Around the World".
The report is available here:
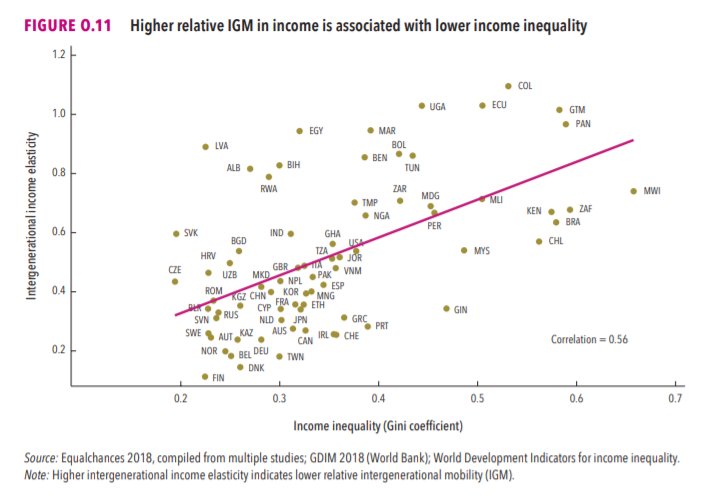
3/The World Bank report has a graph in which it appears to show the same value for China's Gini - under 0.3.
The graph cites the World Development Indicators as its source for the income inequality data.
4/The World Development Indicators are available at the World Bank's website.
Here's the Gini index: https://t.co/MvylQzpX6A
It looks as if the latest estimate for China's Gini is 42.2.
That estimate is from 2012.
5/A Gini of 42.2 would put China in the same neighborhood as the U.S., whose Gini was estimated at 41 in 2013.
I can't find the <30 number anywhere. The only other estimate in the tables for China is from 2008, when it was estimated at 42.8.
This New York Times feature shows China with a Gini Index of less than 30, which would make it more equal than Canada, France, or the Netherlands. https://t.co/g3Sv6DZTDE
That's weird. Income inequality in China is legendary.
Let's check this number.
2/The New York Times cites the World Bank's recent report, "Fair Progress? Economic Mobility across Generations Around the World".
The report is available here:
3/The World Bank report has a graph in which it appears to show the same value for China's Gini - under 0.3.
The graph cites the World Development Indicators as its source for the income inequality data.
4/The World Development Indicators are available at the World Bank's website.
Here's the Gini index: https://t.co/MvylQzpX6A
It looks as if the latest estimate for China's Gini is 42.2.
That estimate is from 2012.
5/A Gini of 42.2 would put China in the same neighborhood as the U.S., whose Gini was estimated at 41 in 2013.
I can't find the <30 number anywhere. The only other estimate in the tables for China is from 2008, when it was estimated at 42.8.