
Assume a country to be like a company, which has income & expenses. Income source can be tax collections & expense can be government employee salaries, defence sending’s, social security schemes etc. (2/13)
Is US going to default on its debt?
This 🧵 will surely help you understand. Do ‘re-tweet’ & help us educated investors (1/13)
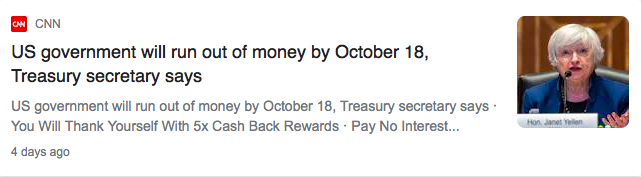
Assume a country to be like a company, which has income & expenses. Income source can be tax collections & expense can be government employee salaries, defence sending’s, social security schemes etc. (2/13)
Similarly US has been borrowing & the total debt today roughly stands at a whooping $28.5T. (3/13)
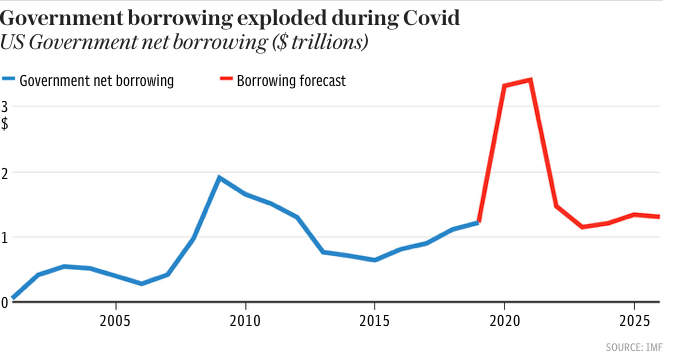
Ideally a yes but they are not allowed to borrow more! (5/13)
During the 1st world war, US understood if they keep spending money on the war, the debt will be a big liability 4 the future generation & hence they introduced a ceiling on the maximum debt US could take. In 1917, this was capped at $1 Billion
Political parties would pass a legislation to increase the debt limits. From $1B in 1917, the debt ceiling has been moved up multiple times to the current $28.5T (https://t.co/XaLWSSGxN5), which is about to get reached now (7/13)
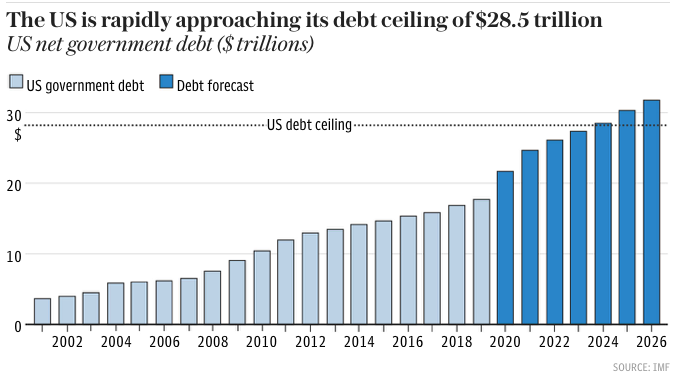
Political parties (Like India has BJP & congress, US has Democrats & Republicans) need to agree on either suspending the debt ceiling all together or increasing the limit of borrowing by passing legislation like they have been doing in the past (8/13)
May be, but republicans r nt in favor of suspension or ⬆️ in the debt ceiling. But this is common, has happened multiple times in the past. Till the legislation is passed, the government shuts down for few days & is back in action as soon as it is passed
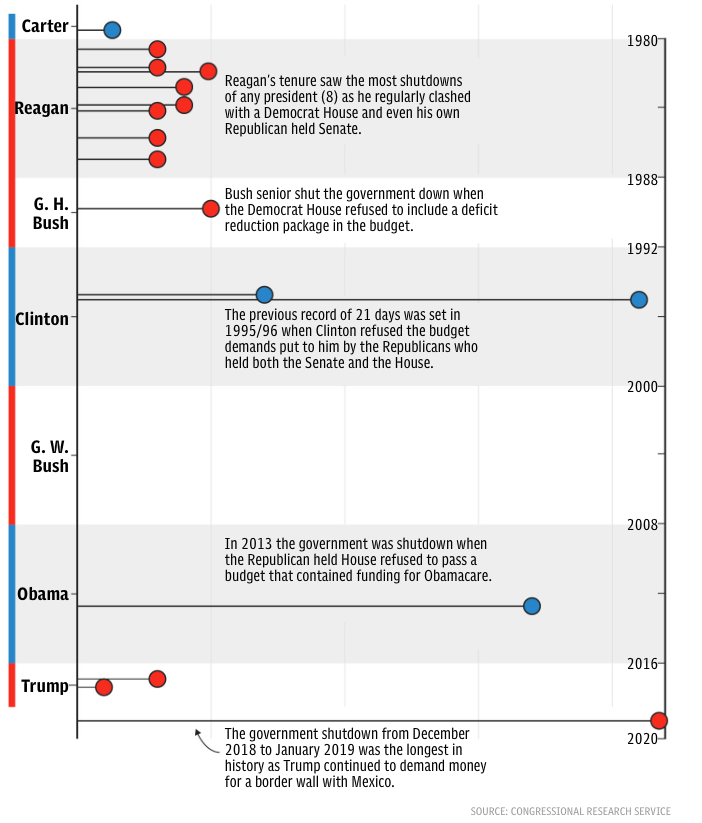
A suspension or rise in the debt ceiling can be passed through a process known as budget reconciliation, due to Democrat's majority in the Senate. But some conservative democrats may not support ⬆️in spending so this may face challenges
Doomsday! US can't borrow more & can default eventually!
-US will not be able to pay salaries to government employees, will not be able to release social security payments, will not be able to pay other liabilities (11/13)
- $ will crash
- Both of the above to have a massive impact on world trade & markets as still 84% of the world trade happens in $ & other countries have huge investments in US treasuries (12/13)
Have earlier written on,
-Sector Analysis - Banking, Paints, Logistic, REIT, InvIT, Sugar, Steel
- Macro
- Debt Markets
- Equity
- Gold
- Personal Finance etc.
You can find them all in the link below https://t.co/UrRt87xaU7 (END)
Here\u2019s a compilation of Personal Finance threads I have written so far. Thank you for motivating me to do it.
— Kirtan A Shah (@KirtanShahCFP) December 13, 2020
Hit the 're-tweet' and help us educated more investors
More from Kirtan A Shah
Personal Finance 101 – My learning’s about investing
This topic is for everyone, whether you manage your money yourself or through your advisor, it will go a long way in managing your finances.
Do re-tweet & help us educate retail investors (1/n)
Subscribe to our YouTube for some interesting educational content around Personal Finance - https://t.co/jvgNEDWiAZ
And you can also join our Telegram channel for regular updates – https://t.co/Ekz6I8pDGt (2/n)
(1) Lets start with Life Insurance
Term Insurance is the best way to take an insurance cover & probably the only product to buy in life insurance. Make sure u disclose all the necessary information before taking the insurance. Smoking, Alcohol, any pre-existing deceases etc(3/n)
Have atleast 10-15 times of your annual income as insurance cover
But there are variants of term insurance that you should avoid (4/n)
(A) Term plan with return of premium
For a non-smoker born on the 1st Jan 1985 & policy term 39 years (till age 75), the regular premium for a 1-cr term insurance is 22,157 (inclusive of GST) but with returns of premium is 42670 (inclusive of GST). An increase of 20,513 (5/n)
This topic is for everyone, whether you manage your money yourself or through your advisor, it will go a long way in managing your finances.
Do re-tweet & help us educate retail investors (1/n)
Subscribe to our YouTube for some interesting educational content around Personal Finance - https://t.co/jvgNEDWiAZ
And you can also join our Telegram channel for regular updates – https://t.co/Ekz6I8pDGt (2/n)
(1) Lets start with Life Insurance
Term Insurance is the best way to take an insurance cover & probably the only product to buy in life insurance. Make sure u disclose all the necessary information before taking the insurance. Smoking, Alcohol, any pre-existing deceases etc(3/n)
Have atleast 10-15 times of your annual income as insurance cover
But there are variants of term insurance that you should avoid (4/n)
(A) Term plan with return of premium
For a non-smoker born on the 1st Jan 1985 & policy term 39 years (till age 75), the regular premium for a 1-cr term insurance is 22,157 (inclusive of GST) but with returns of premium is 42670 (inclusive of GST). An increase of 20,513 (5/n)


You May Also Like




So the cryptocurrency industry has basically two products, one which is relatively benign and doesn't have product market fit, and one which is malignant and does. The industry has a weird superposition of understanding this fact and (strategically?) not understanding it.
The benign product is sovereign programmable money, which is historically a niche interest of folks with a relatively clustered set of beliefs about the state, the literary merit of Snow Crash, and the utility of gold to the modern economy.
This product has narrow appeal and, accordingly, is worth about as much as everything else on a 486 sitting in someone's basement is worth.
The other product is investment scams, which have approximately the best product market fit of anything produced by humans. In no age, in no country, in no city, at no level of sophistication do people consistently say "Actually I would prefer not to get money for nothing."
This product needs the exchanges like they need oxygen, because the value of it is directly tied to having payment rails to move real currency into the ecosystem and some jurisdictional and regulatory legerdemain to stay one step ahead of the banhammer.
If everyone was holding bitcoin on the old x86 in their parents basement, we would be finding a price bottom. The problem is the risk is all pooled at a few brokerages and a network of rotten exchanges with counter party risk that makes AIG circa 2008 look like a good credit.
— Greg Wester (@gwestr) November 25, 2018
The benign product is sovereign programmable money, which is historically a niche interest of folks with a relatively clustered set of beliefs about the state, the literary merit of Snow Crash, and the utility of gold to the modern economy.
This product has narrow appeal and, accordingly, is worth about as much as everything else on a 486 sitting in someone's basement is worth.
The other product is investment scams, which have approximately the best product market fit of anything produced by humans. In no age, in no country, in no city, at no level of sophistication do people consistently say "Actually I would prefer not to get money for nothing."
This product needs the exchanges like they need oxygen, because the value of it is directly tied to having payment rails to move real currency into the ecosystem and some jurisdictional and regulatory legerdemain to stay one step ahead of the banhammer.


