This is actually an interesting question and a correct observation. Many people before you also have made this observation, so I am going to explain this the best I can
Ek baat to hai dada, u like mandi over teji.. Don't u... I mean u play both sides bt still... Im ryt \U0001f911\U0001f911
— VaibhavSharma (@vaibhav2631) September 23, 2022
1. Vega hurts me
2. Theta decay increases.
So, the position does give money, but slowly
1. Vega is in my favour
2. Theta decay slows down and in some cases is totally negated by Vega effect
Plus, falls are faster and rises are slower. Fast means less theta burn, slow means bigger theta burn.
More from Subhadip Nandy
IV - A thread
In financial mathematics, implied volatility of an option contract is
that value of the volatility of the underlying instrument which, when
input in an option pricing model ) will return a theoretical value equal to the current market price of the option (1/n)
Implied volatility, a forward-looking and subjective measure, differs
from historical volatility because the latter is calculated from known
past returns of a security. .
https://t.co/iC5wVf7kvj (2/n)
To understand where Implied Volatility stands in terms of the underlying, implied volatility rank is used to understand its implied volatility from a one year high and low IV.
https://t.co/NFPOidRRcH
https://t.co/qNqinEqaKY
(3/n)
Options traders are always looking at the IV and IVR/IVP. For option
buyers, a low IV environment is best to initiate positions as the
subsequent rise in IV actually helps their positions . Even if the IV
remains flat, the position is not hurt by volatility (4/n)
Option sellers on the other hand are looking for high IV scenarios, where
the subsequent fall in IV ( known a vol crush , most often seen after
earnings/events) helps their positions. Here also, if the IV does not
rise, it does not hurt a seller's positions (5/n)


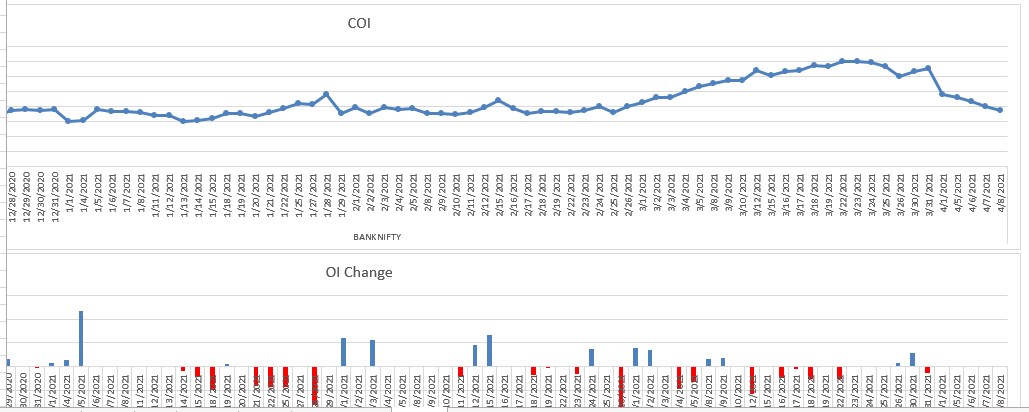
Time I retweeted this 😃
IV - A thread
— Subhadip Nandy (@SubhadipNandy16) September 20, 2018
In financial mathematics, implied volatility of an option contract is
that value of the volatility of the underlying instrument which, when
input in an option pricing model ) will return a theoretical value equal to the current market price of the option (1/n)