#UX and #design friends, we need to talk about estimating. I'd like to share some advice that's come up 3 times this week, in hopes it's useful. And it's echoed, by the way, in the BUSINESS OF UX course @EliNatoli and I are teaching at my UX 365 Academy (link at the end).

(1/12)

Avoiding wars with clients is a matter of how you structure your engagements, along with how you spell out what you're doing in your proposals/contracts. That starts with estimating.

The biggest 2 rules I follow are these:

(2/12)
1. I do not EVER estimate a project in full from start-to-finish.

2. Once we're past initial Discovery (see below), I estimate in small chunks, e.g. "here's what will take us to the next iteration/review."

(3/12)
NEVER estimate past the point where you may get new information based on a build/test cycle.

Believe me when I say that you'll be wrong every time. Ask me how I know ;-)

(4/12)
So instead, first, I estimate a Consult/Discovery part that details what I think we need to do to get a handle on what's actually wrong here, and how long that will take.

For example...

(5/12)
...every client I have agrees to a time span, either me working directly with their team or me evaluating what they have and speaking with them. That is all pure fact-finding, nothing more. Getting the lay of the land (including politically).

(6/12)
There are no deliverables other than a summary of

(1) What I think is wrong, and

(2) What I suggest they do next, with or without me.

There's no scope for them to adjust, in other words. Nothing to change their minds about.

(7/12)
"I'm giving you X days/weeks, and at the end of that I'll tell you what I see."

Once I get past that, if they need me to advise on design/dev for an iteration, I chunk that out as a timeframe as well. X weeks with X review points, and those reviews are specified.

(8/12)
1 full day onsite, a 3-hour ZOOM session, etc. I don't ever estimate past a single iteration cycle or sprint, because there are too many unknowns, too many opportunities for them to second guess and change their minds about what they want to do.

(9/12)
This keeps the emphasis on the span of time instead of the tactical work at hand. If I give them a cost for 3 weeks, that figure reflects the distinct possibility that I may or may not spend 8 hours a day every day of those 3 weeks.

(10/12)
Whether I do or don't is irrelevant; I'm saying to them, "if you want my undivided attention for X weeks, here's what that costs."
You have to base your estimates on the only thing you can CONTROL, which is the TIME you spend.

Estimating tasks is a losing proposition.

(11/12)
You limit your risk by charging appropriately for that time — all of it. And you're also not inviting debates about how long something should or shouldn't take.

I hope that's helpful, and again — there's a LOT more where that came from here: https://t.co/s5JuUZnIEo

(12/12)

More from Tech

Recently, the @CNIL issued a decision regarding the GDPR compliance of an unknown French adtech company named "Vectaury". It may seem like small fry, but the decision has potential wide-ranging impacts for Google, the IAB framework, and today's adtech. It's thread time! 👇

It's all in French, but if you're up for it you can read:
• Their blog post (lacks the most interesting details):
https://t.co/PHkDcOT1hy
• Their high-level legal decision: https://t.co/hwpiEvjodt
• The full notification: https://t.co/QQB7rfynha

I've read it so you needn't!

Vectaury was collecting geolocation data in order to create profiles (eg. people who often go to this or that type of shop) so as to power ad targeting. They operate through embedded SDKs and ad bidding, making them invisible to users.

The @CNIL notes that profiling based off of geolocation presents particular risks since it reveals people's movements and habits. As risky, the processing requires consent — this will be the heart of their assessment.

Interesting point: they justify the decision in part because of how many people COULD be targeted in this way (rather than how many have — though they note that too). Because it's on a phone, and many have phones, it is considered large-scale processing no matter what.
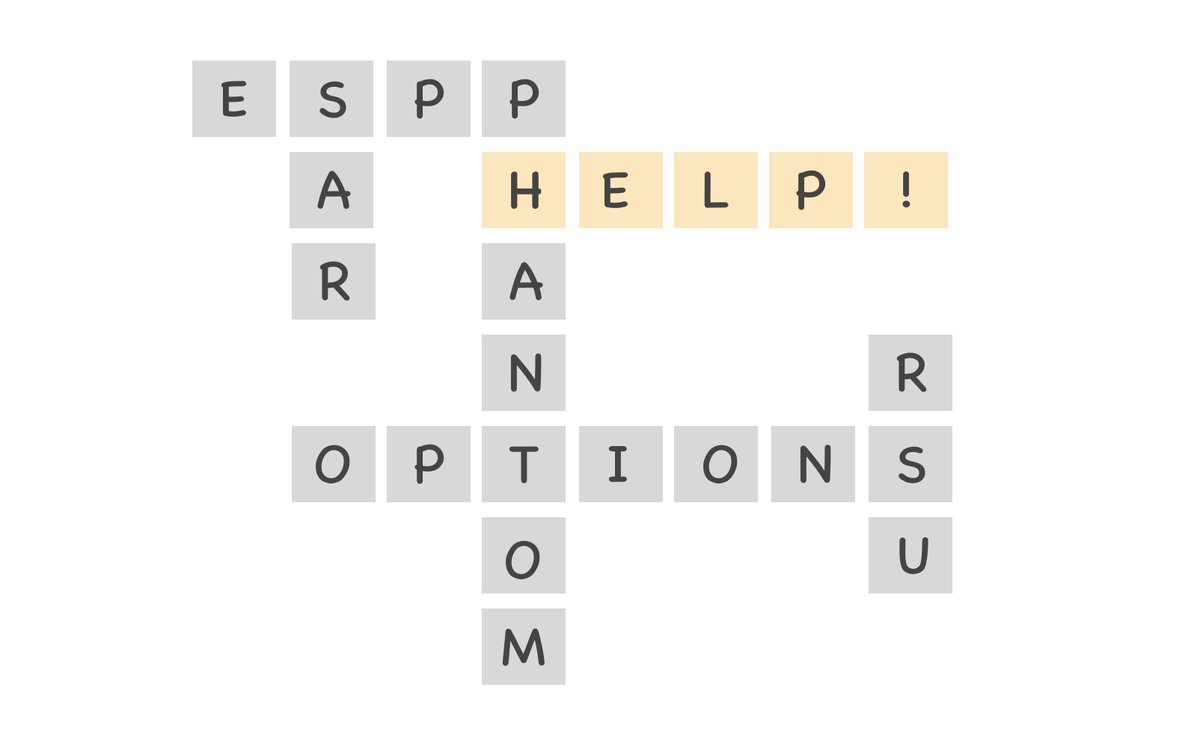
The 12 most important pieces of information and concepts I wish I knew about equity, as a software engineer.

A thread.

1. Equity is something Big Tech and high-growth companies award to software engineers at all levels. The more senior you are, the bigger the ratio can be:


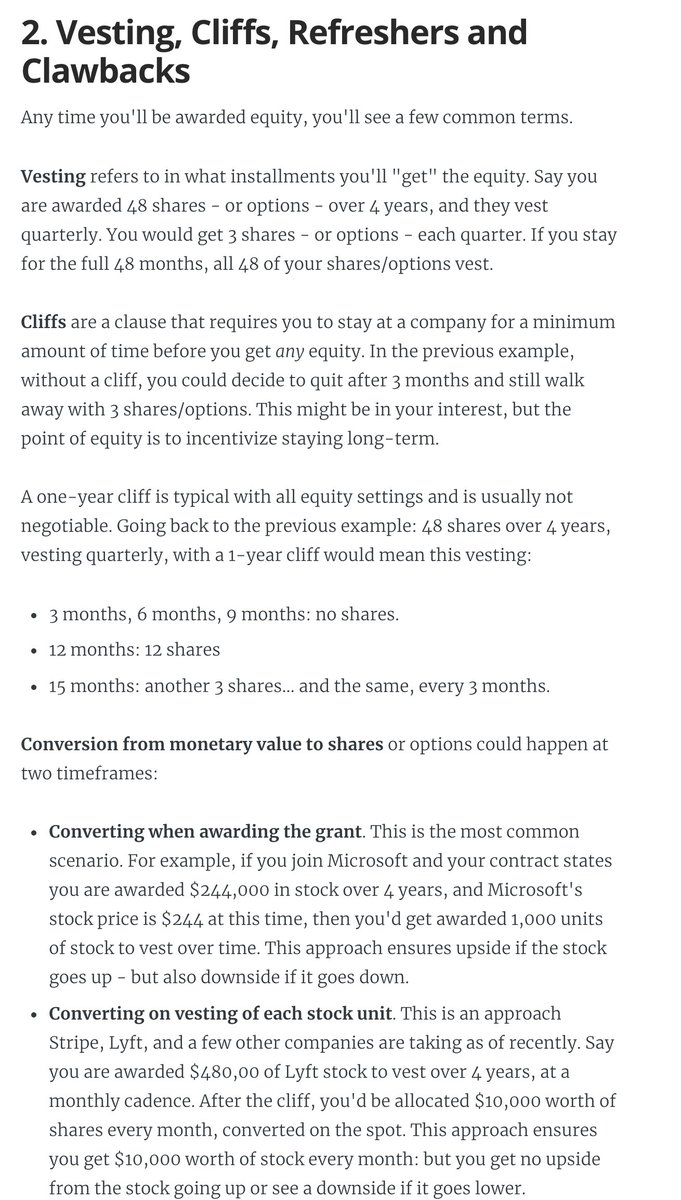
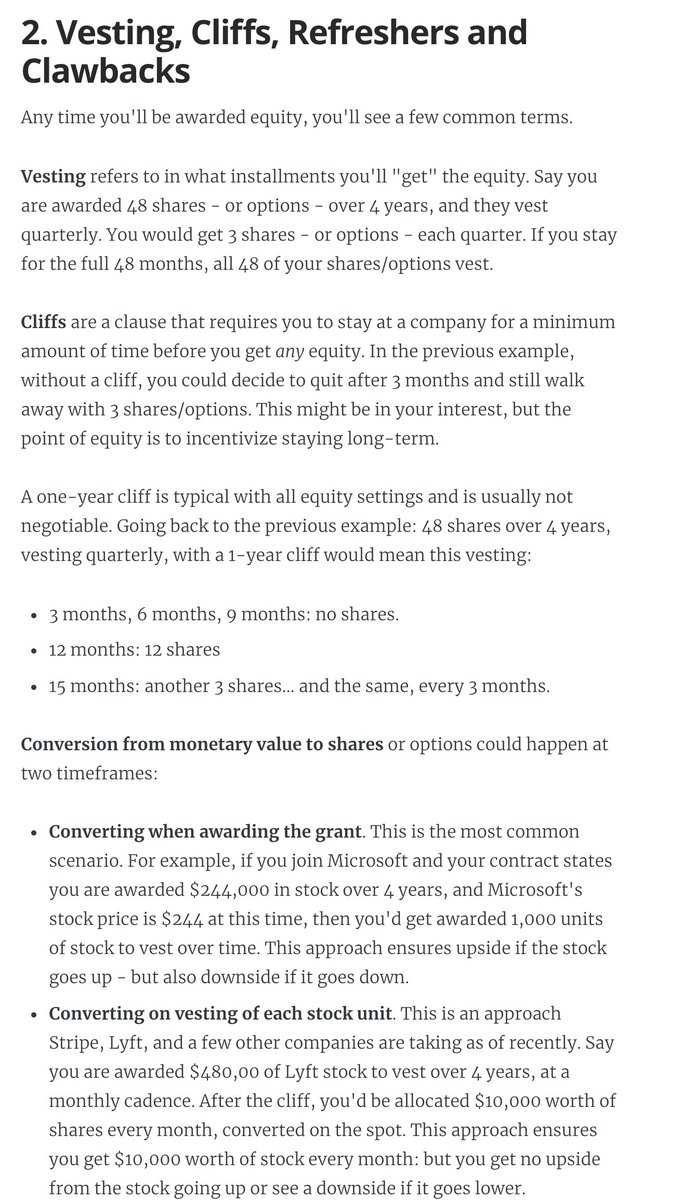
2. Vesting, cliffs, refreshers, and sign-on clawbacks.

If you get awarded equity, you'll want to understand vesting and cliffs. A 1-year cliff is pretty common in most places that award equity.

Read more in this blog post I wrote:
https://t.co/WxQ9pQh2mY


3. Stock options / ESOPs.

The most common form of equity compensation at early-stage startups that are high-growth.

And there are *so* many pitfalls you'll want to be aware of. You need to do your research on this: I can't do justice in a tweet.

https://t.co/cudLn3ngqi


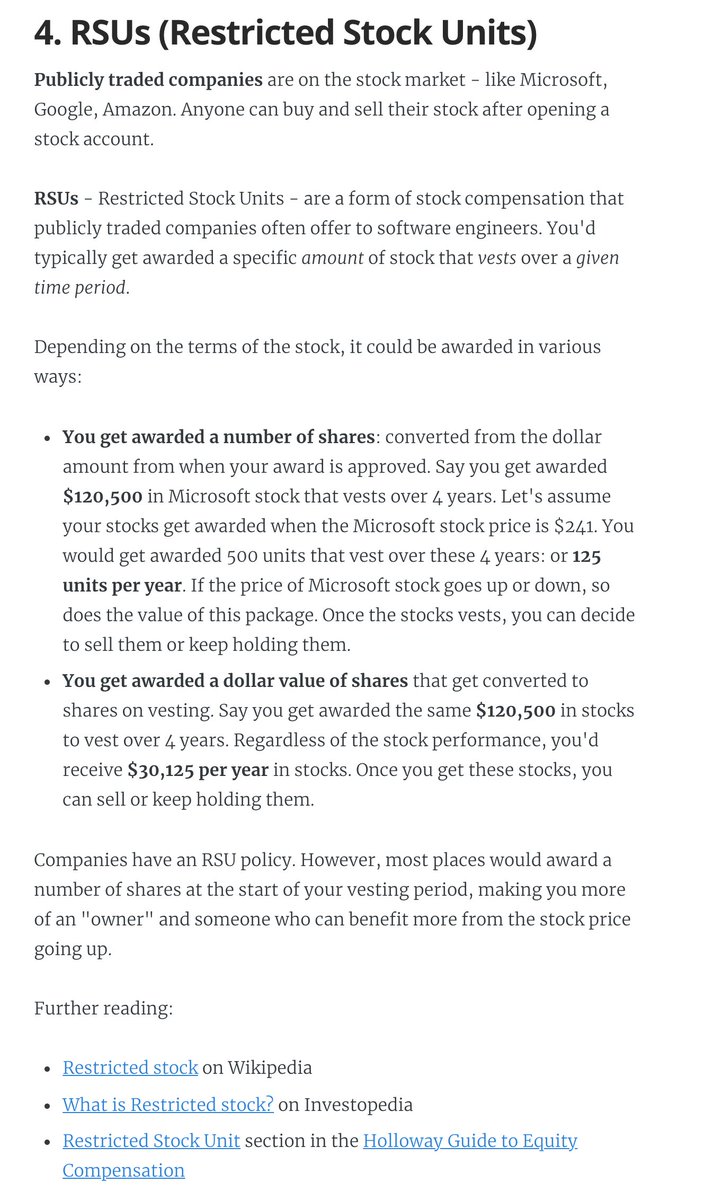
4. RSUs (Restricted Stock Units)

A common form of equity compensation for publicly traded companies and Big Tech. One of the easier types of equity to understand: https://t.co/a5xU1H9IHP

5. Double-trigger RSUs. Typically RSUs for pre-IPO companies. I got these at Uber.


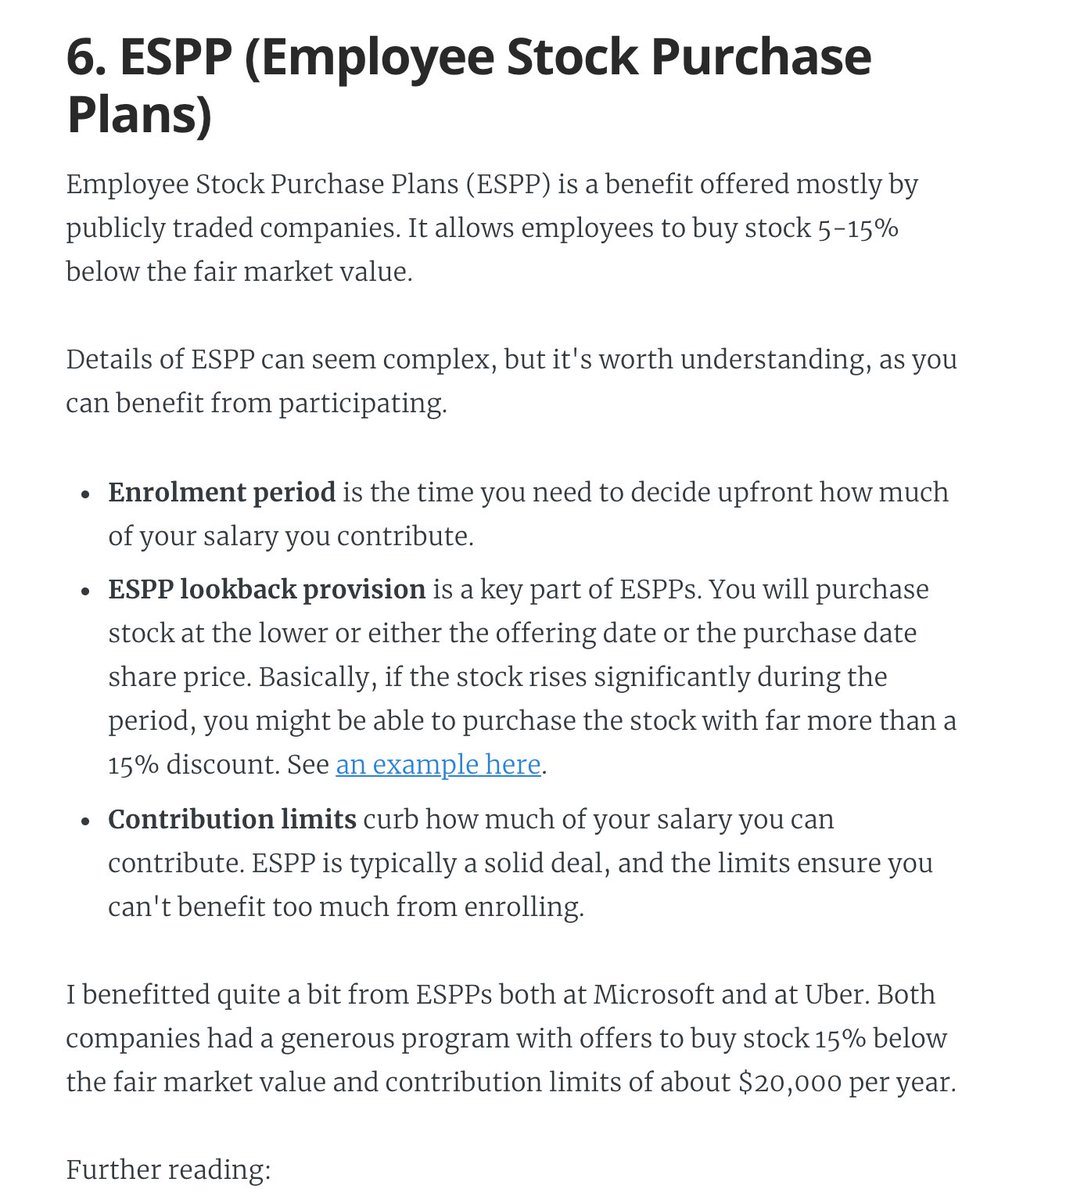
6. ESPP: a (typically) amazing employee perk at publicly traded companies. There's always risk, but this plan can typically offer good upsides.

7. Phantom shares. An interesting setup similar to RSUs... but you don't own stocks. Not frequent, but e.g. Adyen goes with this plan.

You May Also Like

A THREAD ON @SarangSood

Decoded his way of analysis/logics for everyone to easily understand.

Have covered:
1. Analysis of volatility, how to foresee/signs.
2. Workbook
3. When to sell options
4. Diff category of days
5. How movement of option prices tell us what will happen

1. Keeps following volatility super closely.

Makes 7-8 different strategies to give him a sense of what's going on.

Whichever gives highest profit he trades in.


2. Theta falls when market moves.
Falls where market is headed towards not on our original position.


3. If you're an options seller then sell only when volatility is dropping, there is a high probability of you making the right trade and getting profit as a result

He believes in a market operator, if market mover sells volatility Sarang Sir joins him.


4. Theta decay vs Fall in vega

Sell when Vega is falling rather than for theta decay. You won't be trapped and higher probability of making profit.