A ThreadЁЯз╡on various #IncomeTax #Deductions.

Must read for everyone.

A simple & legitimate way to to save taxes every year!

(RT to maximize reach.)

Money Saved is Money Earned !

#IncomeTax #Tax #ELSS #TaxSaving #Investing #TaxPlanning

Images Courtesy : Internet.

When the month of March starts or is about to end suddenly everyone remembers one thing #TaxSaving ...

This is where #TaxDeductions come into picture.

Deductions allowed under #IncomeTax act help you reduce your taxable income.
People normally know a bit about Section 80C Deduction which allows a person to claim a deduction of Rs 1.5 lakh on total income.

But there are various other common deductions which anyone can claim.

This thread is about such common deductions.
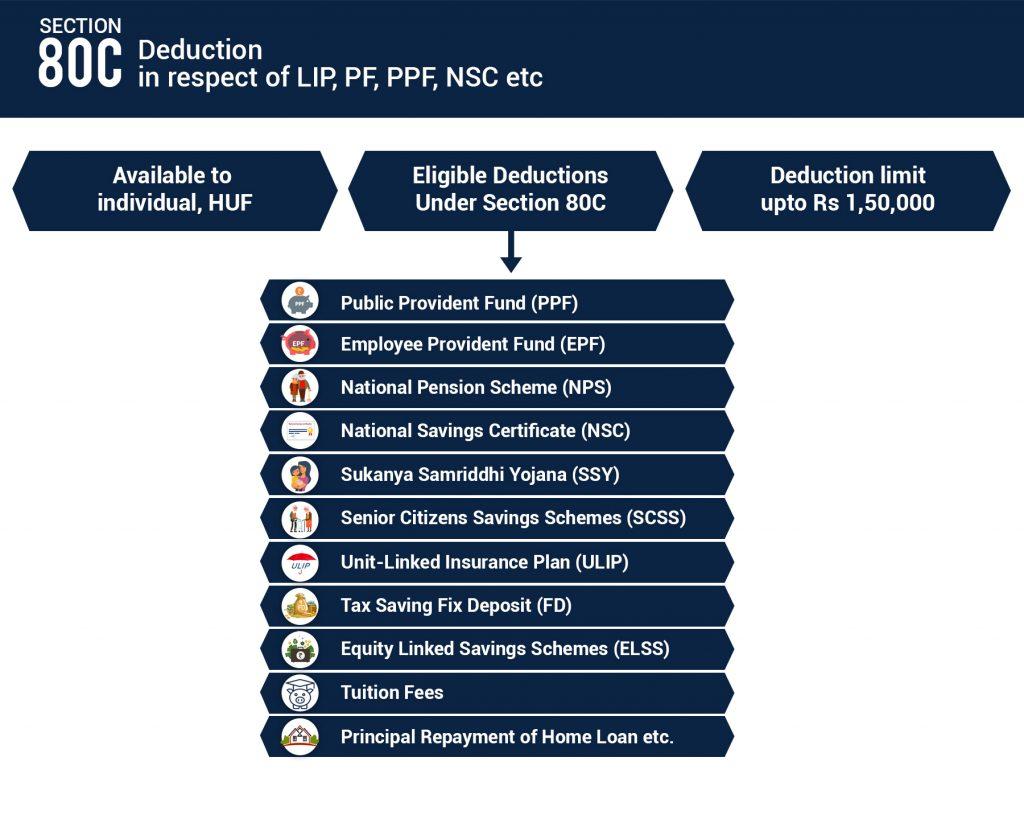
Section 80C: for #TaxSaving #Investments & Payments.

A deduction up to Rs 1,50,000 is allowed under #Section80C of Income Tax Act 1961 in respect of eligible investments or expenditures.

* See Note Ahead

Discussed in detail ЁЯСЙ https://t.co/a5tbOUJoHQ

#TaxSaving #TaxPlanning
Section 80CCC: for Contribution to #PensionFund

A deduction up to Rs 1,50,000 is available under Section 80CCC of #IncomeTax Act 1961 in respect of contributions made by an individual towards specified pension funds.

* See Note Ahead

#TaxSaving #TaxPlanning #Investing
Section 80CCD: for Contribution to #PensionFund of Central Govt

A deduction up to Rs 1,50,000 is available under Section 80CCD of Income Tax Act 1961 in respect of contributions made towards National Pension Scheme (NPS) or Atal Pension Yojana (APY)

* See Note Ahead

#TaxSaving
*
Note : The deduction limit of Rs 1.5 lakh deduction of Section 80C includes Section 80C, Section 80CCC & Section 80CCD.

#TaxSaving #TaxPlanning #Investing
Section 80CCD (1B): for contribution to National Pension Scheme (NPS)

An additional deduction of Rs 50,000 is made available in Budget 2015 through sub-section 1B, thereby raising maximum deduction available under Section 80CCD to Rs. 2,00,000

#TaxSaving #TaxPlanning #Investing
Section 80CCF: for Contributions to Long-term Infrastructure Bonds.

A deduction up to Rs 20,000 is available under Section 80CCF of Income Tax Act 1961 in respect of subscription to long-term infrastructure bonds.

#TaxSaving #TaxPlanning #Investing
Section 80TTA: for Savings Interest

A deduction up to Rs 10,000 is available under Section 80TTA of Income Tax Act 1961 in respect of interest on deposits in savings account.

#TaxSaving #TaxPlanning #Investing
Section 80TTB: Interest Deduction on deposits for Senior Citizens

A deduction up to Rs 50,000 is available (only for senior citizens) under Section 80TTA of Income Tax Act 1961 in respect of interest on both deposits in savings account and fixed deposits in banks.

#TaxSaving
Section 80D: for Medical Insurance Premium

A deduction up to Rs 25,000 (50,000 for senior citizens) is available under #Section80D of #IncomeTax Act 1961 in respect of health insurance premium for self, spouse and dependent children and parents.

#TaxSaving #TaxPlanning
Section 80DD: for Differently abled Dependant

A deduction of Rs 75,000 (Rs 1,25,000 for severe disabilities) is allowed under #Section80DD of Income Tax Act 1961 in respect of maintenance including medical treatment of a dependant who is a person with disability.

#TaxSaving
Section 80DDB: for Treatment of Specified Diseases

A deduction up to Rs 40,000 (1,00,000 for senior citizens) is available under #Section80DDB of #IncomeTax Act 1961 in respect of medical treatment of certain specified ailments for self or dependent.

#TaxSaving #TaxPlanning
Section 80U: for Individuals with Disability

A deduction of Rs 75,000 (Rs 1,25,000 for severe disabilities) is allowed under #Section80U of Income Tax Act 1961 for people suffering from certain disabilities.

#TaxSaving #TaxPlanning #Investing
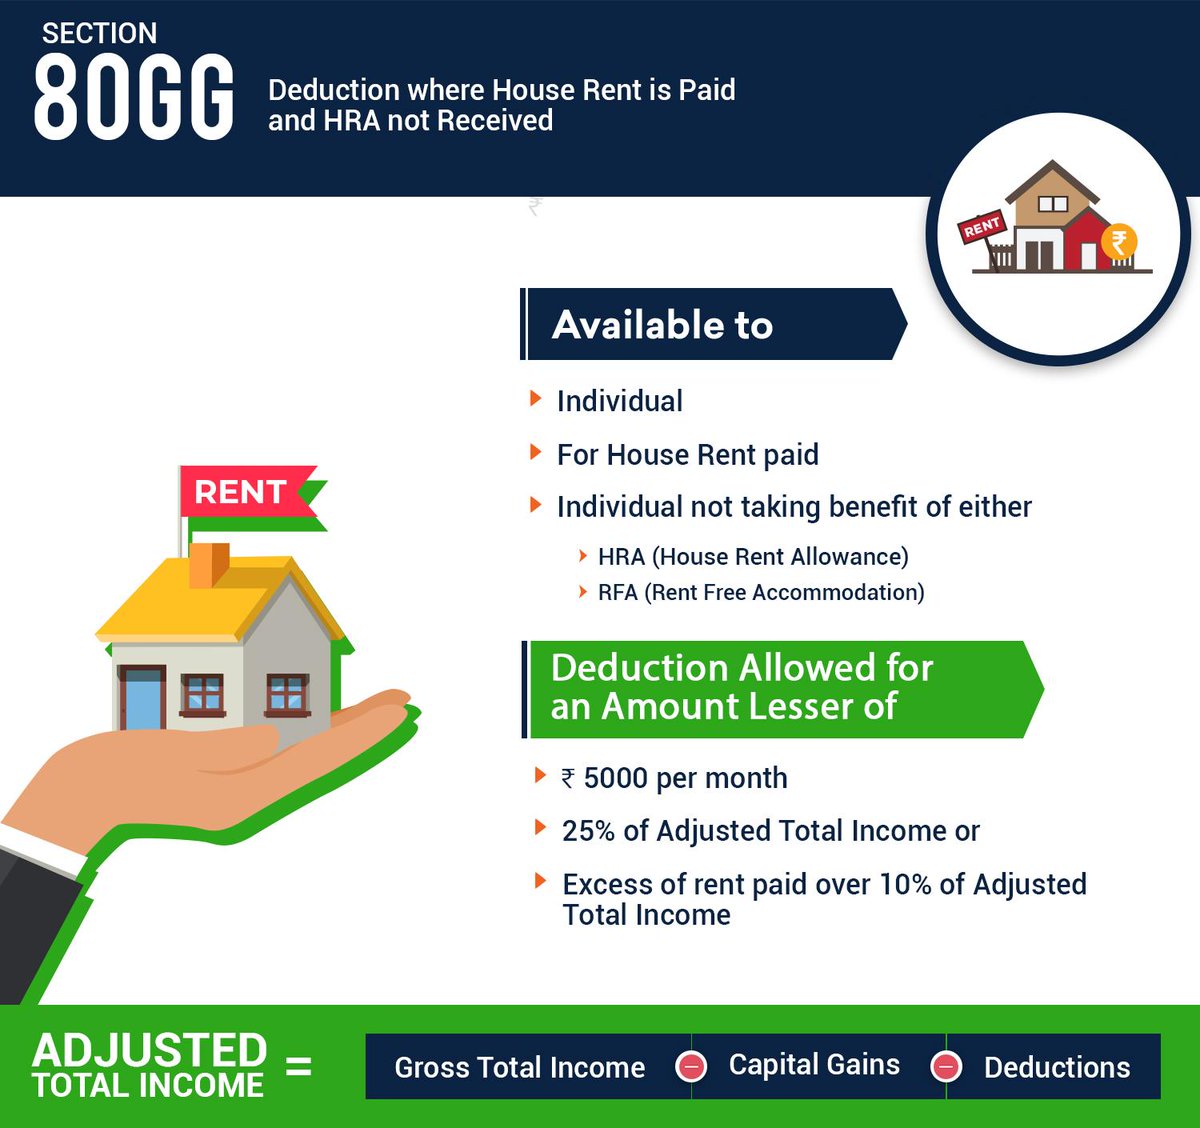
Section 80GG: for Rent paid

A deduction up to Rs 60,000 per year is allowed under #Section80GG of #IncomeTax Act 1961 in respect of rents paid when HRA is not received.

#IncomeTaxIndia #TaxSaving #TaxPlanning
Section 80E: for Interest on Education Loan

A deduction (without any maximum limit) is available under #Section80E of #IncomeTax Act 1961 in respect of interest paid for a period of 8 years on loan taken for higher education.

#TaxSaving #TaxPlanning #Investing
Section 80EE: for First Time Home Buyer

A deduction up to Rs 50,000 is available under #Section80EE of Income Tax Act 1961 in respect of interest on loan taken for residential house property.

#TaxSaving #TaxPlanning #investing
Section 80EEB: for Purchase of Electric Vehicle

A deduction up to Rs 1,50,000 is available under #Section80EEB of Income Tax Act 1961 in respect of interest paid on loan taken for purchase of an electric vehicle for personal or business use.

#EV #ElectricVehicle #TaxSaving
Section 80G: for Donation to Charitable Organisations

A 50% or 100% deduction (without any maximum limit) is available under #Section80G of #IncomeTax Act 1961 in respect of donations to certain funds, charitable institutions, etc.

#TaxSaving #TaxPlanning #Investing
Section 80GGB: for Donation to Political Parties (deduction for companies)

A deduction (without any maximum limit) is available to companies under Section 80GGB in respect of contributions given by companies to political parties.
Section 80GGC: for Donation to Political Parties (deductions for individuals)

A deduction (without any maximum limit) is available to individuals under #Section80GGB of #IncomeTax Act 1961 in respect of contributions given by individuals to political parties.

#TaxSaving
ЁЯМЯImportant Note & Disclaimer ЁЯМЯ

I am not a qualified C.A. This thread is to provide only basic idea about common tax deductions.

For more details, it is advisable to contact your C.A and discuss with C.A about various #TaxDeductions whose benefit you can claim.

#TaxPlanning

You May Also Like

This is a pretty valiant attempt to defend the "Feminist Glaciology" article, which says conventional wisdom is wrong, and this is a solid piece of scholarship. I'll beg to differ, because I think Jeffery, here, is confusing scholarship with "saying things that seem right".


The article is, at heart, deeply weird, even essentialist. Here, for example, is the claim that proposing climate engineering is a "man" thing. Also a "man" thing: attempting to get distance from a topic, approaching it in a disinterested fashion.


Also a "man" thingтАФphysical courage. (I guess, not quite: physical courage "co-constitutes" masculinist glaciology along with nationalism and colonialism.)


There's criticism of a New York Times article that talks about glaciology adventures, which makes a similar point.


At the heart of this chunk is the claim that glaciology excludes women because of a narrative of scientific objectivity and physical adventure. This is a strong claim! It's not enough to say, hey, sure, sounds good. Is it true?
рдорд╣рд╛рднрд╛рд░рдд рдХреА рдХрд╣рд╛рдиреА рдХреМрди рдирд╣реАрдВ рдЬрд╛рдирддрд╛редрд▓реЗрдХрд┐рди рдХреНрдпрд╛ рдЖрдкрдХреЛ рдкрддрд╛ рд╣реИ рдХрд┐ рдорд╣рд╛рднрд╛рд░рдд рдХреЗ рдЬреНрдпрд╛рджрд╛рддрд░ рдкрд╛рддреНрд░ рдХрд┐рд╕реА рди рдХрд┐рд╕реА рд╢реНрд░рд╛рдк рдореЗрдВ рдлрдВрд╕реЗ рдереЗредрдЕрдЧрд░ рдпреЗ рд╢реНрд░рд╛рдк рди рд╣реЛрддреЗ рддреЛ рдХрджрд╛рдЪрд┐рдд рдорд╣рд╛рднрд╛рд░рдд рдХреА рдХрд╣рд╛рдиреА рдХреБрдЫ рдФрд░ рд╣реЛрддреАредрд╣рд┐рдиреНрджреБ рдкреМрд░рд╛рдгрд┐рдХ рдЧреНрд░рдВрдереЛрдВ рдореЗрдВ рд╡рд┐рднрд┐рдиреНрди рд╢реНрд░рд╛рдкреЛрдВ рдХрд╛ рд╡рд░реНрдгрди рдорд┐рд▓рддрд╛ рд╣реИ рд╡ рд╣рд░ рд╢реНрд░рд╛рдк рдХреЗ рдкреАрдЫреЗ рдХреЛрдИ рдХрд╣рд╛рдиреА рдЕрд╡рд╢реНрдп рд╣реЛрддреА рд╣реИред


рдЖрдЗрдП рдЖрдЬ рдЬрд╛рдирддреЗ рд╣реИрдВ рдорд╣рд╛рднрд╛рд░рдд рдХрдерд╛ рдореЗрдВ рд╡рд░реНрдгрд┐рдд рдХреБрдЫ рд╢реНрд░рд╛рдкреЛрдВ рдХреЗ рдмрд╛рд░реЗ рдореЗрдВред

1) рд░рд╛рдЬрд╛ рдкрд╛рдгреНрдбреБ рдХреЛ рдЛрд╖рд┐ рдХрд┐рдиреНрджрдо рдХрд╛ рд╢реНрд░рд╛рдк

рдПрдХрдмрд╛рд░ рдорд╣рд╛рд░рд╛рдЬ рдкрд╛рдгреНрдбреБ рд╢рд┐рдХрд╛рд░ рдЦреЗрд▓рдиреЗ рд╡рди рдЧрдПредрдЭрд╛рдбрд┐рдпреЛрдВ рдХреЗ рдкреАрдЫреЗ рдХреБрдЫ рд╣рд┐рд▓ рд░рд╣рд╛ рдерд╛ред рдореГрдЧ рд╣реИ рд╕реЛрдЪрдХрд░ рд░рд╛рдЬрд╛ рдиреЗ рдмрд╛рдг рдЪрд▓рд╛рдпрд╛ рдЬреЛ рдЬрд╛рдХрд░ рдЛрд╖рд┐ рдХрд┐рдиреНрджрдо рдФрд░ рдЙрдирдХреА рдкрддреНрдиреА рдХреЛ рд▓рдЧрд╛редрд╡реЗ рджреЛрдиреЛ рд░рддрд┐-рдХреНрд░реАрдбрд╝рд╛ рдореЗрдВ рд▓рд┐рдкреНрдд рдереЗред

рдЬрдм рд░рд╛рдЬрд╛ рдиреЗ рдЙрдиреНрд╣реЗрдВ рджреЗрдЦрд╛ рддреЛ рдмрд╣реБрдд рджреБрдЦреА рд╣реБрдП рдХрд┐ рдпреЗ рдореБрдЭрд╕реЗ рдХреНрдпрд╛ рдкрд╛рдк рд╣реЛ рдЧрдпрд╛редрдмрд╣реБрдд рдХреНрд╖рдорд╛ рдпрд╛рдЪрдирд╛ рдХреЗ рдмрд╛рдж рднреА рдХрд┐рдиреНрджрдо рдЛрд╖рд┐ рдиреЗ рдкрд╛рдгреНрдбреБ рдХреЛ рд╢реНрд░рд╛рдк рджреЗ рджрд┐рдпрд╛ рдХрд┐ рдЬрдм рднреА рд╡реЛ рдХрд┐рд╕реА рд╕реНрддреНрд░реА рдХреЛ рдХрд╛рдо рднрд╛рд╡рдирд╛ рд╕реЗ рд╕реНрдкрд░реНрд╢ рдХрд░реЗрдВрдЧреЗ рдЙрд╕реА рдХреНрд╖рдг рдЙрдирдХреА рдореГрддреНрдпреБ рд╣реЛ рдЬрд╛рдПрдЧреАредрдкрд╢реНрдЪрд╛рддрд╛рдк рдХрд░рдиреЗ, рд╡реЗ рд╕рд┐рдВрд╣рд╛рд╕рди рдкреЗ рдЕрдиреНрдзреЗ рд░рд╛рдЬрд╛ рдзреГрддрд░рд╛рд╖реНрдЯреНрд░ рдХреЛ рдмреИрдард╛рдХрд░...


..рд╕реНрд╡рдпрдВ рдЕрдкрдиреА рд░рд╛рдирд┐рдпреЛрдВ рдХреБрдВрддреА рд╡ рдорд╛рджреНрд░реА рдХреЗ рд╕рд╛рде рд╡рди рдЪрд▓реЗ рдЧрдПредрдкрд╛рдВрдбрд╡реЛрдВ рдХрд╛ рдЬрдиреНрдо рднреА рдХреБрдВрддреА рдХреЛ рдЛрд╖рд┐ рджреБрд░реНрд╡рд╛рд╕рд╛ рджреНрд╡рд╛рд░рд╛ рджрд┐рдП рдЧрдП рдордВрддреНрд░ рд╕реЗ рд╣реБрдЖ рдерд╛ рдЬрд┐рд╕рдореЗ рдХрд┐рд╕реА рднреА рджреЗрд╡ рдХрд╛ рд╕реНрдорд░рдг рдХрд░ рдЙрд╕ рджреЗрд╡ рд╕реЗ рдХреБрдВрддреА,рдкреБрддреНрд░ рдкреНрд░рд╛рдкреНрдд рдХрд░ рд╕рдХрддреА рдереАредрдПрдХ рдмрд╛рд░ рдорд╛рджреНрд░реА рдкреЗ рдореЛрд╣рд┐рдд рд╣реЛ рдЬрдм рдкрд╛рдВрдбреБ рдиреЗ рдЙрд╕реЗ рд╕реНрдкрд░реНрд╢ рдХрд┐рдпрд╛,рдЙрд╕реА рдХреНрд╖рдг рдкрд╛рдВрдбреБ рдХреА рдореГрддреНрдпреБ рд╣реЛрдЧрдпреАред


2) рдЙрд░реНрд╡рд╢реА рдХрд╛ рдЕрд░реНрдЬреБрди рдХреЛ рд╢реНрд░рд╛рдк

рдорд╣рд╛рднрд╛рд░рдд рдпреБрджреНрдз рд╕реЗ рдкрд╣рд▓реЗ рдЬрдм рдЕрд░реНрдЬреБрди рджрд┐рд╡реНрдпрд╛рд╕реНрддреНрд░ рдкреНрд░рд╛рдкреНрдд рдХрд░рдиреЗ рд╕реНрд╡рд░реНрдЧ рдЧрдП рддреЛ рд╡рд╣рд╛рдВ рдЙрд░реНрд╡рд╢реА рдирд╛рдо рдХреА рдЕрдкреНрд╕рд░рд╛ рдЙрди рдкрд░ рдореЛрд╣рд┐рдд рд╣реЛ рдЧрдпреАред рдЕрд░реНрдЬреБрди рдиреЗ рдЬрдм рдЙрдиреНрд╣реЗрдВ рдЕрдкрдиреА рдорд╛рддрд╛ рдХреЗ рд╕рдорд╛рди рдмрддрд╛рдпрд╛ рддреЛ рдпрд╣ рд╕реБрдирдХрд░ рдЙрд░реНрд╡рд╢реА рдХреНрд░реЛрдзрд┐рдд рд╣реЛ рдЧрдпреА рдФрд░ рдЕрд░реНрдЬреБрди рдХреЛ рд╢реНрд░рд╛рдк рджреЗ рдбрд╛рд▓рд╛ рдХрд┐ рддреБрдо рдирдкреБрдВрд╕рдХ рдХреА рднрд╛рдВрддрд┐...
1/12

RT-PCR corona (test) scam

Symptomatic people are tested for one and only one respiratory virus. This means that other acute respiratory infections are reclassified as


2/12

It is tested exquisitely with a hypersensitive non-specific RT-PCR test / Ct >35 (>30 is nonsense, >35 is madness), without considering Ct and clinical context. This means that more acute respiratory infections are reclassified as


3/12

The Drosten RT-PCR test is fabricated in a way that each country and laboratory perform it differently at too high Ct and that the high rate of false positives increases massively due to cross-reaction with other (corona) viruses in the "flu


4/12

Even asymptomatic, previously called healthy, people are tested (en masse) in this way, although there is no epidemiologically relevant asymptomatic transmission. This means that even healthy people are declared as COVID


5/12

Deaths within 28 days after a positive RT-PCR test from whatever cause are designated as deaths WITH COVID. This means that other causes of death are reclassified as