It's amongst the very few banks that have survived for over 100 years and has remained profitable.
A thread 🧵about a bank whose 2nd name is "Consistency" and it's name is - CITY UNION BANK
Grab a cup of water and relax because it's gonna be a verryyyy long thread.
And don't forget to Re-tweet for wider reach.
It's amongst the very few banks that have survived for over 100 years and has remained profitable.
So banking is a realllly simple business but at the same time it's not.
So why would a person deposit it's money in a bank?
Because 1st of all, you can't keep that much amount lying at your house and 2nd of all you get some interest on the money that you've deposited with them.
So let's try to understand it with an example - Bank is giving 4% on deposits & charges 7% on the loans that they've given.
So 7% - 4% = 3%
(Interest received - Interest paid/Average assets = Net Interest Margin)
Think of it as Net Profit Margin in any other business.
What if someone doesn't pay the money back? How will the bank pay the depositors back in case they want to withdraw their money?
They're called NPA or Non Performing Asset.
Suppose if somebody hasn't paid any EMI or the principle amount for 90 days they're classified as NPA.
So the amount of money that has to be set aside is knows as "Provision".
So as I said earlier if somebody hasn't paid the interest or principle amount back for 90 days that is known as Gross Non performing Asset or GNPA.
And remember we set aside some money in case of potential loss?
GNPA - Provisions = NNPA
So now that've understood what Net Interest Margin, GNPA, NNPA & provision are let's try to understand few other important concepts like - CASA, CRAR, Treasury operations, Provision Coverage Ratio etc
So CASA means = Current Account - Saving Account
So in bank we can open two types of accounts (Broadly speaking) - Savings account or current account.
And we normal people open saving account to keep the extra money somewhere safe.
There are many other types of accounts in a bank like - Business accounts, Salary accounts etc etc.
Because on current account banks doesn't have to pay any interest & on saving account they have to say low interest as compared to fixed deposits or bonds and it's stick in nature.
That's why banks with high CASA ratio can earn more money because their interest out go is lower as compared to a bank who has more raised money
In CASA also, the higher the retail deposits the better as compared to a single customer with a large account.
CASA RATIO = CASA DEPOSTIS/TOTAL DEPOSITS (As a thumb rule - Higher the better)
So if you remember I told you about something called NPA, right?
That if someone hasn't paid back the interest or principle amount for more than 90 days, they're qualified as NPA.
But what if someone hasn't paid back for say 30 days or 60 days
Here comes the concept of SMA or Special Mentioned Accounts.
We have SMA 0 - If the stress has remained overdue for 0 - 30 days
SMA 1 - If the stress has remained overdue for 30-60 days
SMA 2 - If the stress has remained overdue for 6- -90 days.
It means - Capital Adequacy Ratio (CAR) is the ratio of a bank’s capital in relation to its risk-weighted assets and current liabilities.
I has two components - Tier 1 & Tier 2 capital.
Tier 1 - Tier 1 capital can be used to absorb losses without a bank having to stop its operations.
And the combination of both Tier 1 + Tier 2 should be more than 10.5% including the buffer.
It's simple - Tier 1 + Tier 2/Risk Weighted Assets = Risk weighted Assets.
You don't need to calculate this, you can find it in their investor presentation.
As for the thumb rule remember one thing, For a bank it should be above 10.5%
And for high risk Microfinance NBFCs etc, it should be around 20-25%.
One really interesting thing about this bank is that, in it's history of more than 110 years, it has seen only 7 CEO's till date. Yes you heard it right, Only 7 CEO's
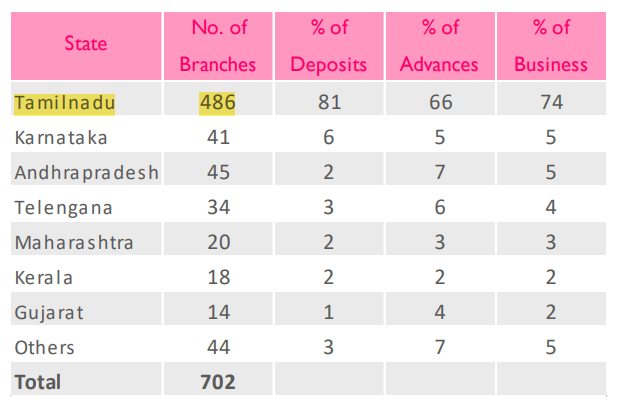
As i said earlier, it's a regionally focused bank with 486 branches out of 700 in just Tamil nadu.
66% Of the advances are from Tamil Nadu
81% Deposits are from Tamil Nadu
(High geographical Concentration)
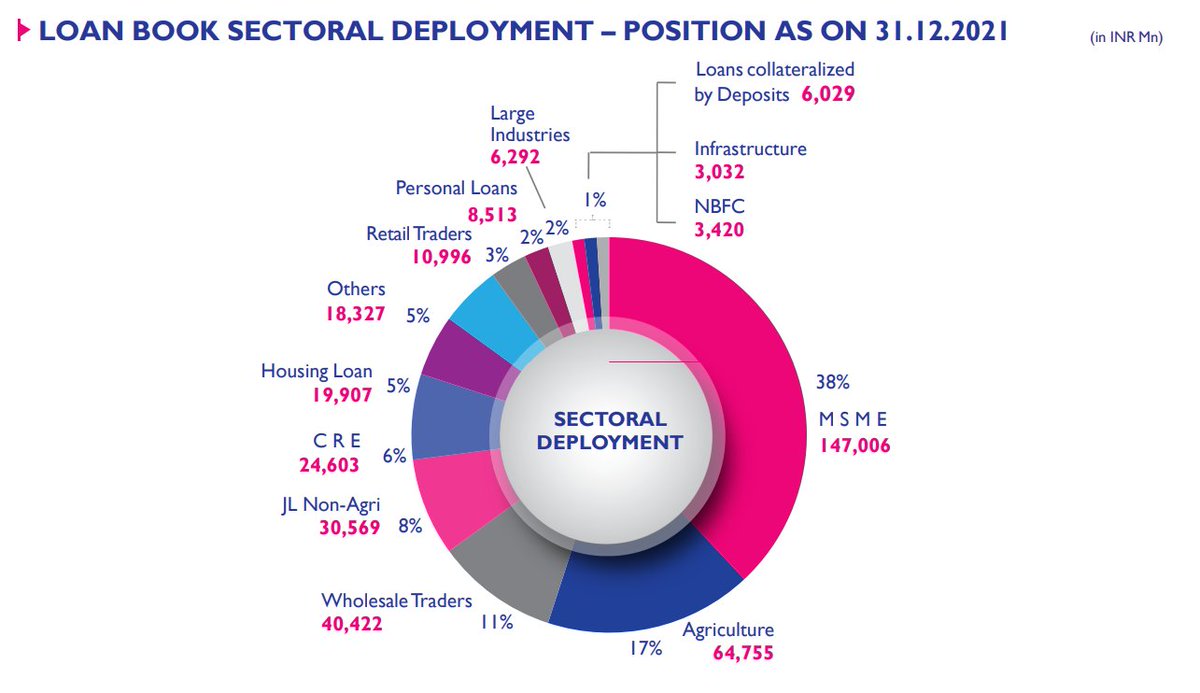
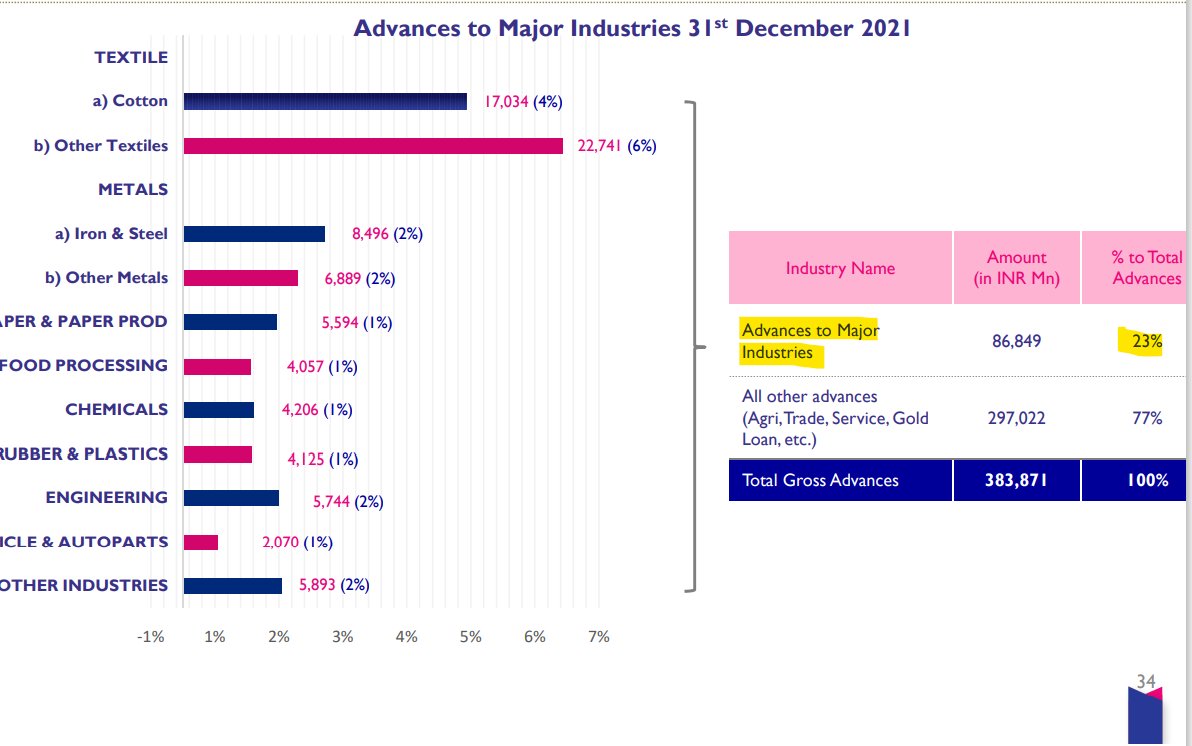
66% loan book is to these segments (High risk as these segments are very vulnerable to economic condition)
38% - MSME
17% - Agriculture
11% - Wholesale Traders
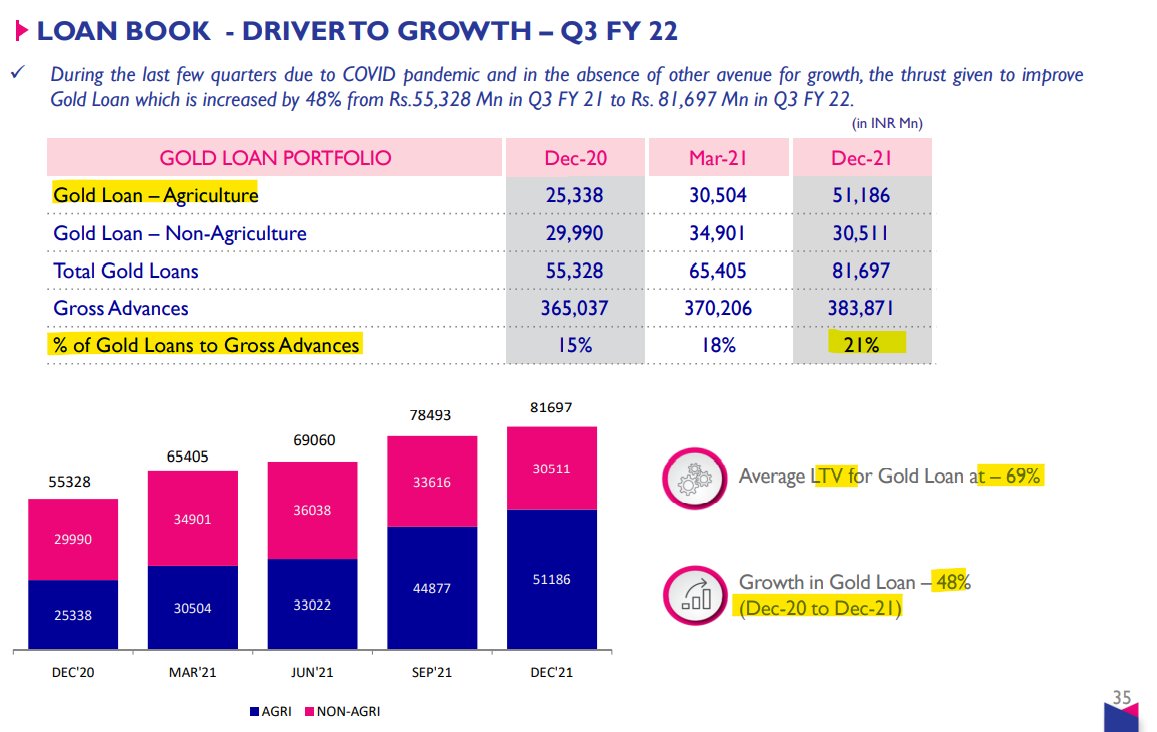
For past one year, gold loans have grown at - 48%
And LTV (Loan to Value) ratio for them is - 69%
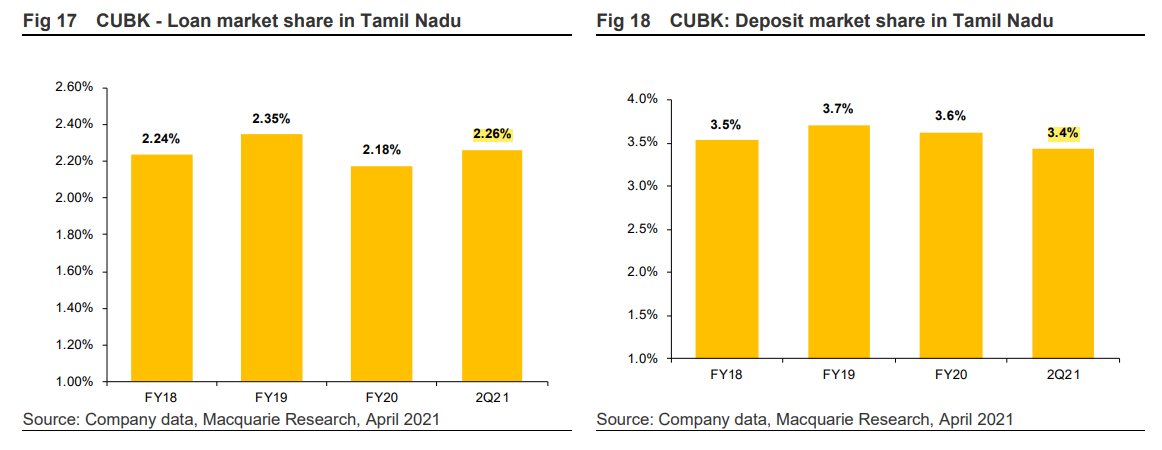
Their total market share in Tamil Nadu in Advances is 2.26% & in deposits its - 3.4%
Huge Runway for growth in the state itself if they can capture market share.
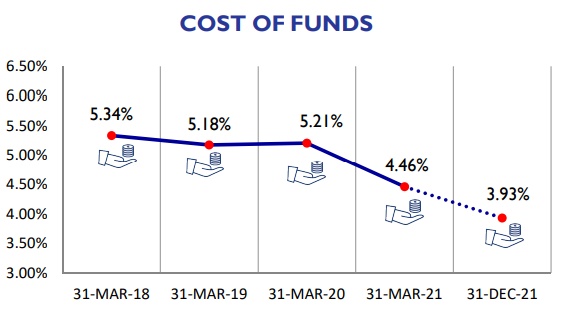
COF is high as compared to peers due to lower CASA - 32% (In the latest quarterly update, Q4FY22)
Concentration of top 20 Depositos is low around - 9%
and concentration of top 20 Advances is also low around - 5.4%
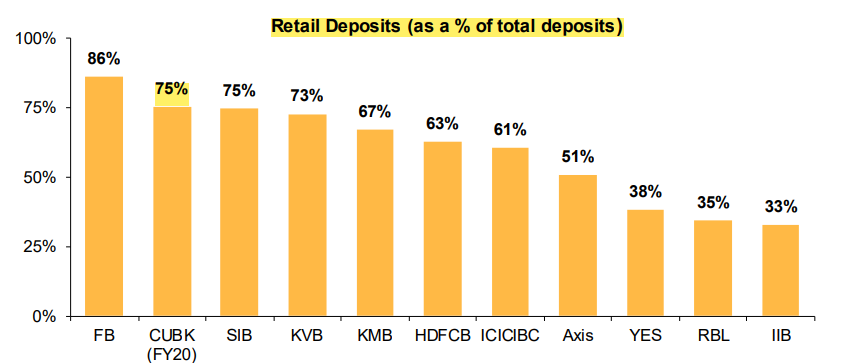
And since 2018 it has been around 11%
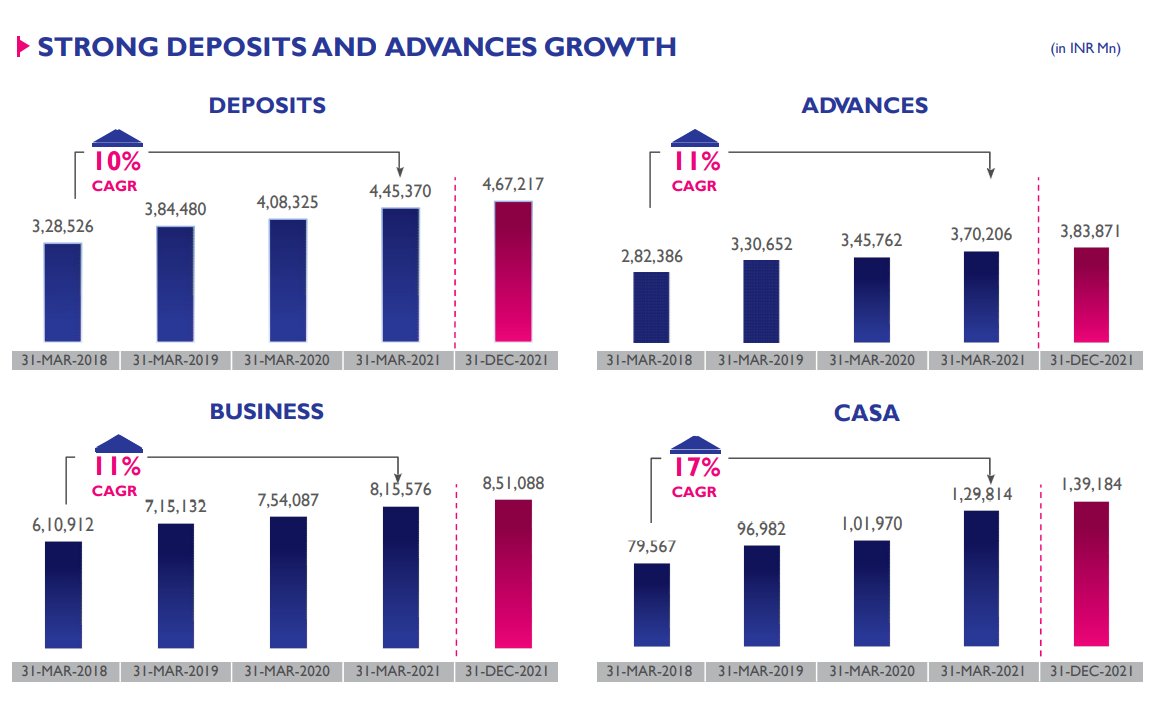
The has successfully maintained ROE of 14% from past 10 years, even in the downcycle.
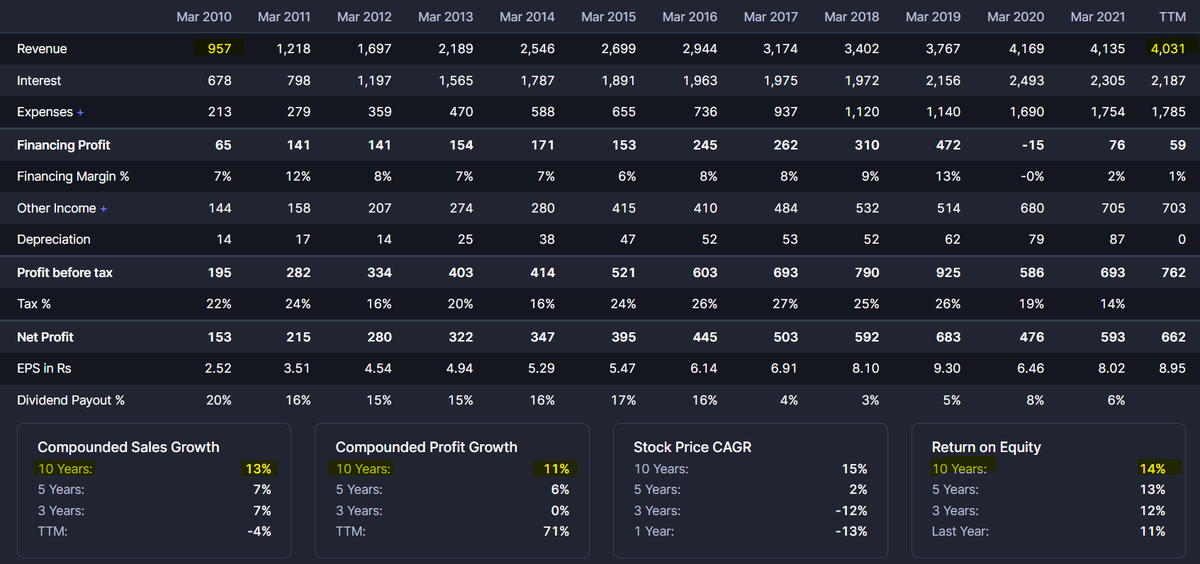
Deposits grew from 40k Cr in Q4 FY20 to 46K Cr in Q3FY22
Advances grew from 34k Cr to 38K Cr.
NIMs have remained stable around 4%
NPA shot up from 3% to >5%.
ROE dipped to 10-11%
ROA has been below 1.5%
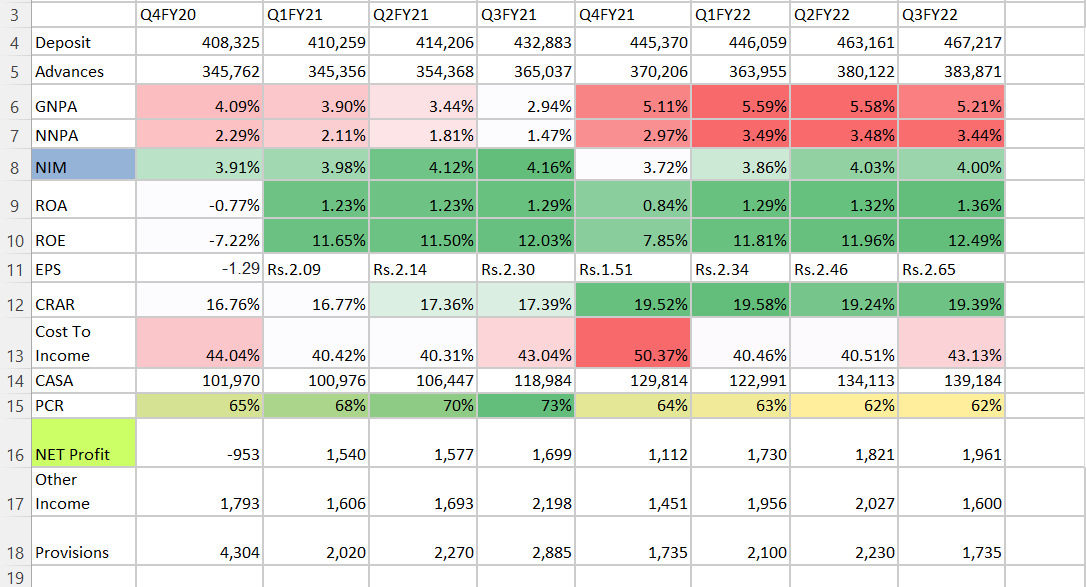
But after hitting a high of 5.59% in Q1FY22, NPAs have been coming down as thing are getting stable.
- Have maintained ROA of > 1.5% from 2010-2020
- ROE >14%
- Around 1-1.2% Credit Cost ( Even after giving high risk loans like MSME & Agriculture Loans)
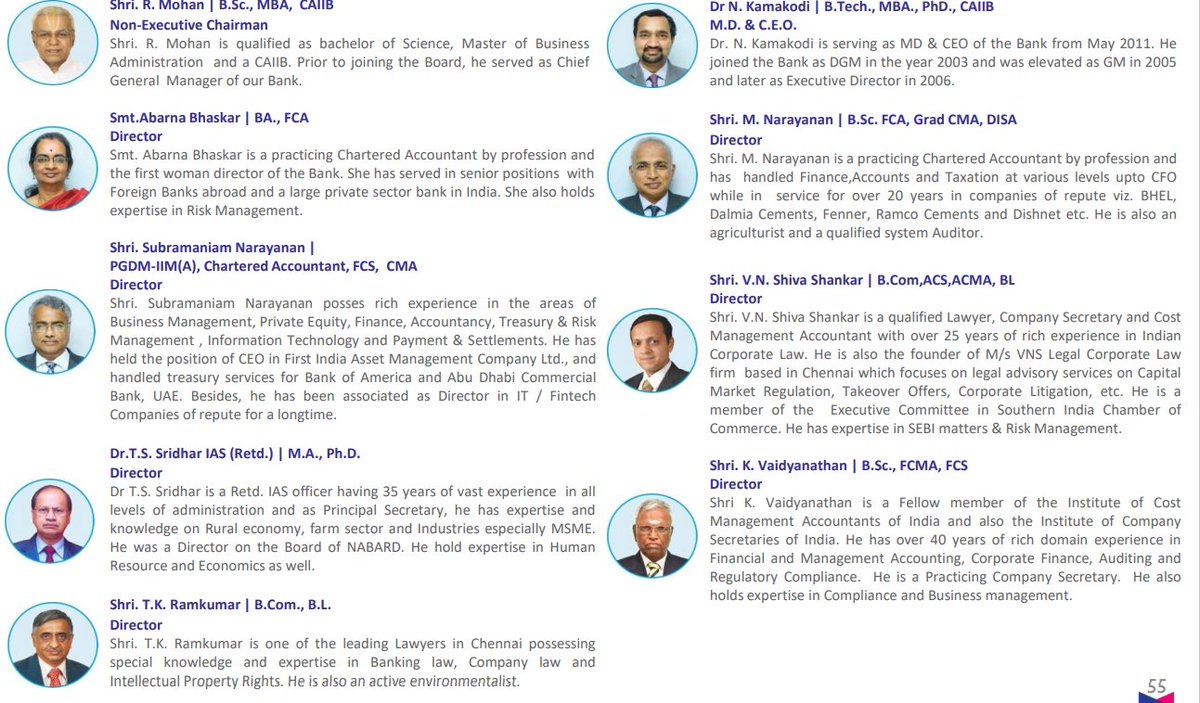
- 89% directors on board are independent directors
- Has added 45 branches & 300 employees every year from 2010-2020
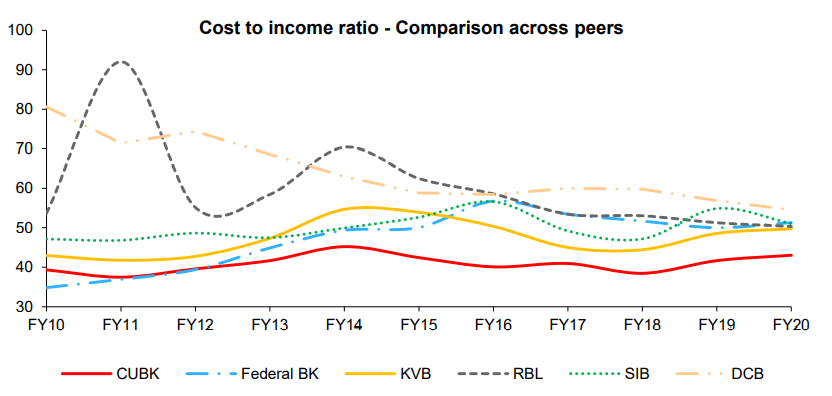
- Cost to income Ratio has been lower around 40-43% , which is lower than it's peers.
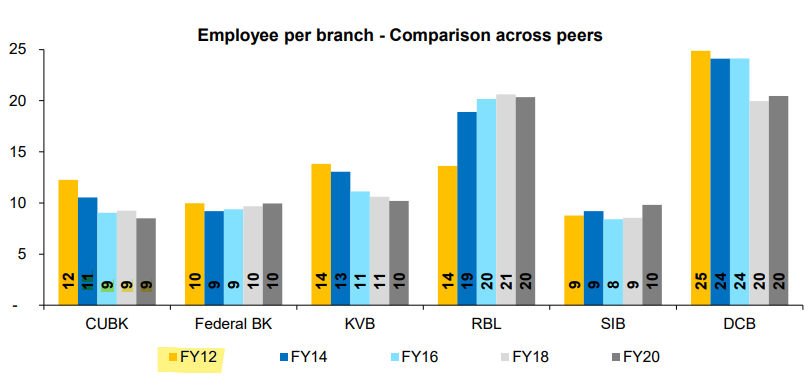
- Lower staff expense as compared to peers.
- Fully integrated mobile banking App
- Key chain debit card & Smart watch payment system
- Was amongst the earliest bank to embark on digital journey, hired TCS for Core Banking Solutions back in around 2001.

Mr N kamakodi one of the most trusted and respected banker have been the CEO since 2011
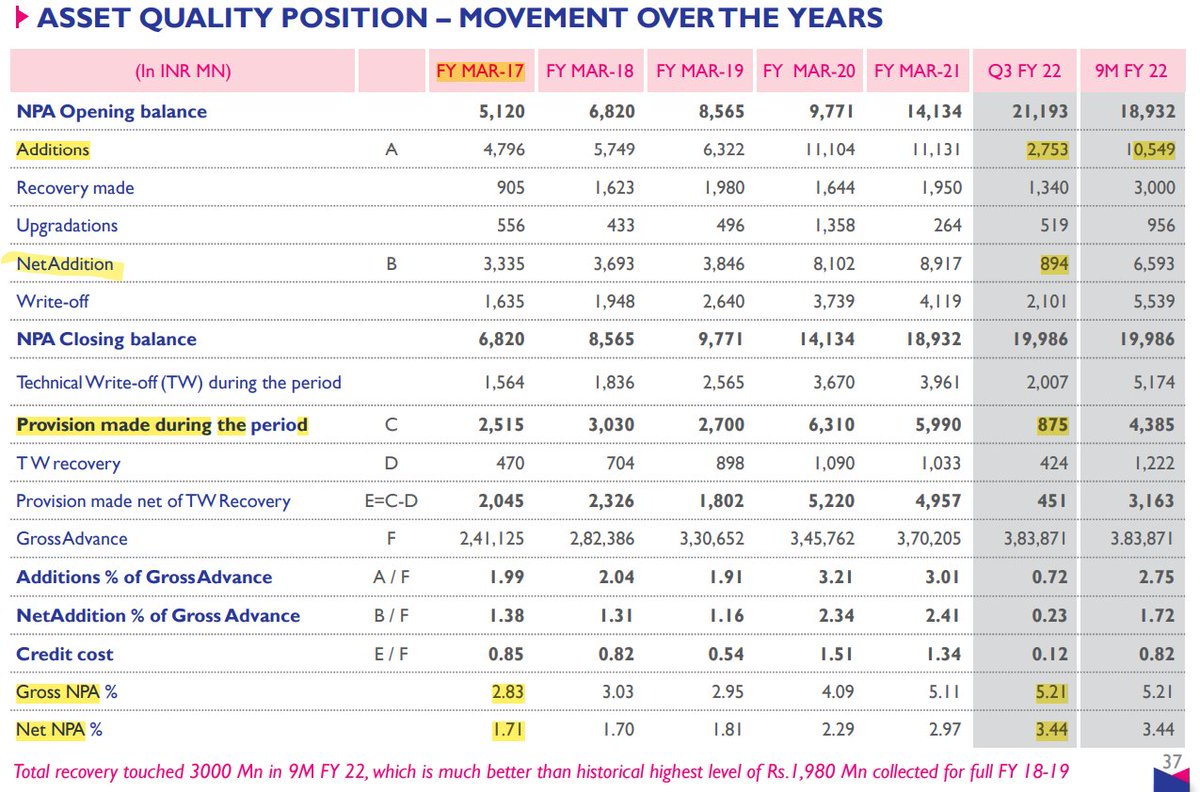
Good thing is, provisions have come down & new additions are also coming down.
Gold loan portfolio is strong with <1% NPA.
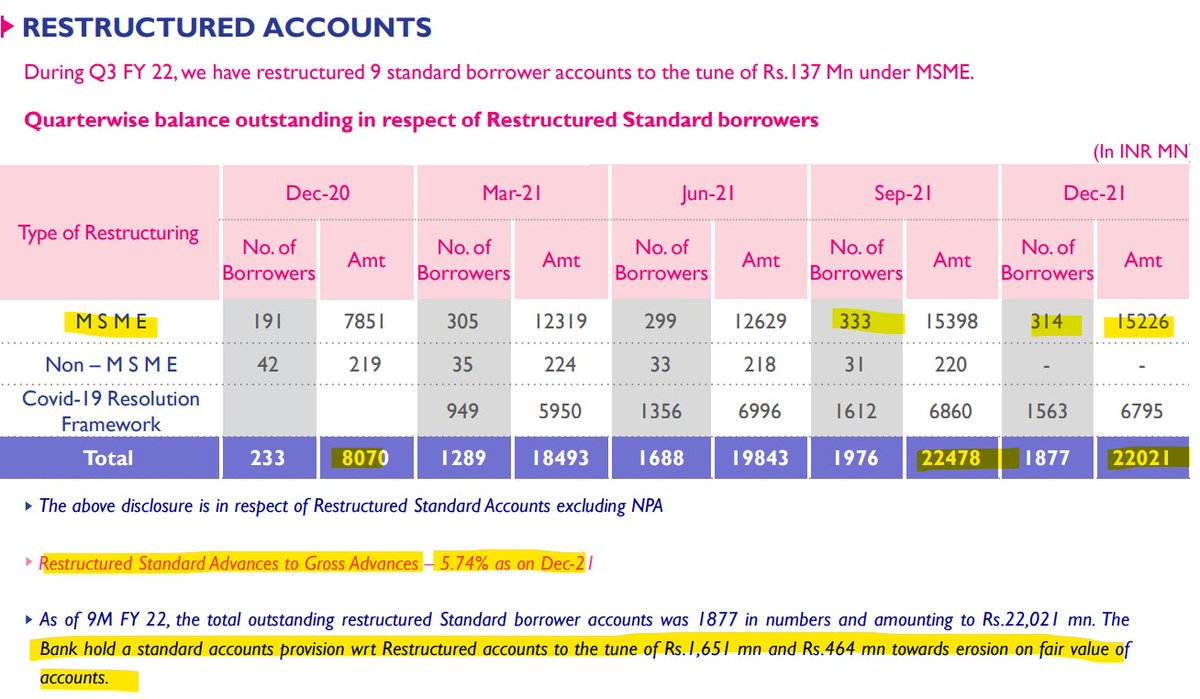
Total no. of restructured accounts have come down QoQ.
Bank holds around 1400 Cr provision for restructures accounts.
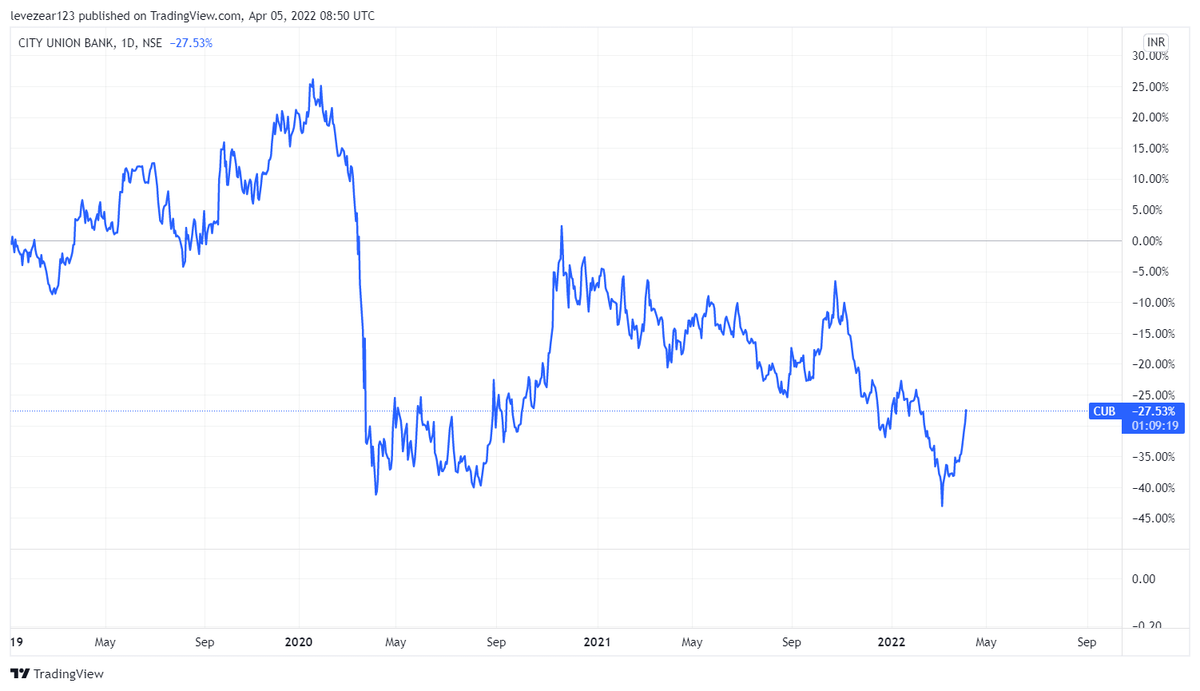
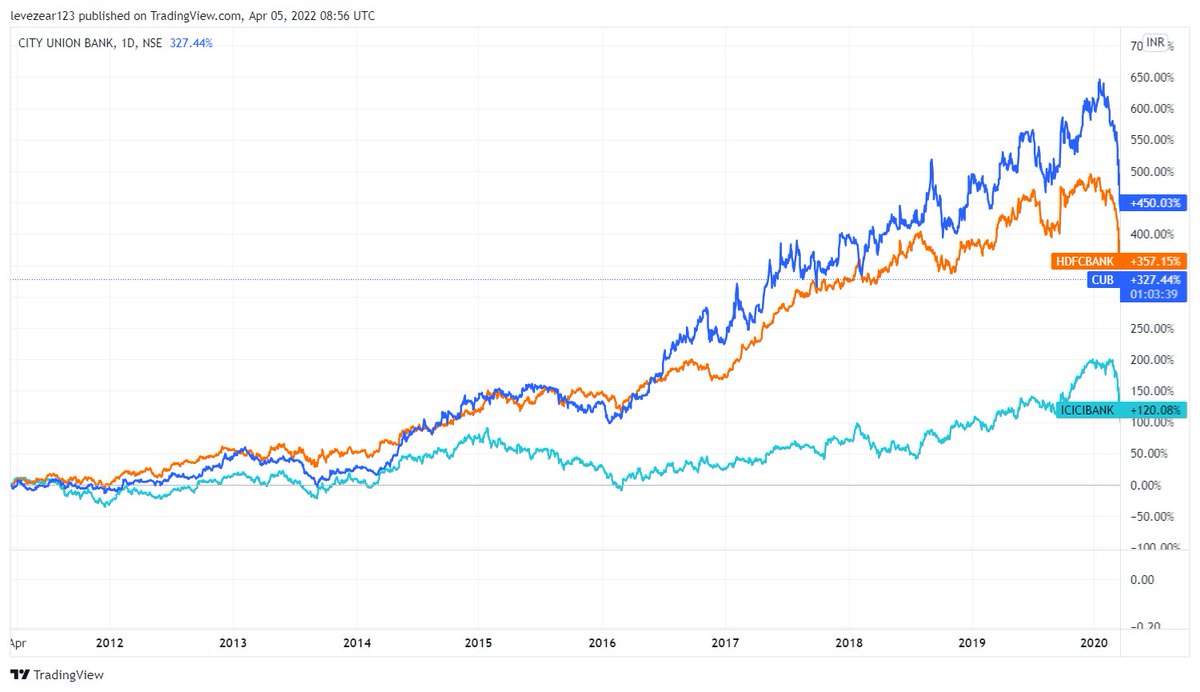
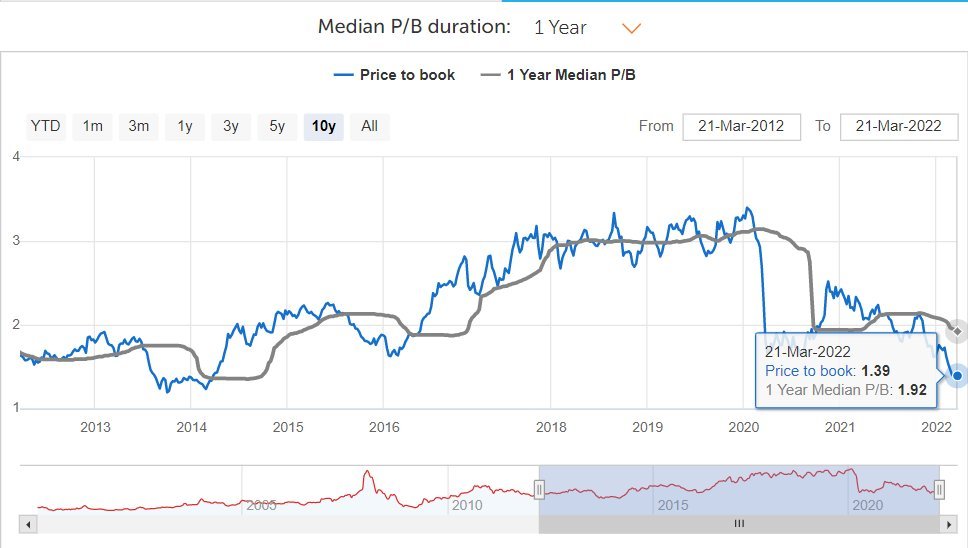
Currently available near decade low p/b can be a good opportunity.
Disclosure - Invested, Not a recommendation
@suru27 @shubhfin @saketreddy @ishmohit1 @soicfinance @sahil_vi @DrdhimanBhatta1 @Arthavruksha12 @badola_arjun
https://t.co/hTp6BSDF8r
A thread \U0001f9f5about a bank whose 2nd name is "Consistency" and it's name is - CITY UNION BANK
— The Average Trader. (@icanseeyourpix2) April 5, 2022
Grab a cup of water and relax because it's gonna be a verryyyy long thread.
And don't forget to Re-tweet for wider reach. pic.twitter.com/mfSgSBfLNc
You May Also Like



12 TRADING SETUPS which experts are using.
These setups I found from the following 4 accounts:
1. @Pathik_Trader
2. @sourabhsiso19
3. @ITRADE191
4. @DillikiBiili
Share for the benefit of everyone.
Here are the setups from @Pathik_Trader Sir first.
1. Open Drive (Intraday Setup explained)
Bactesting results of Open Drive
2. Two Price Action setups to get good long side trade for intraday.
1. PDC Acts as Support
2. PDH Acts as
Example of PDC/PDH Setup given
These setups I found from the following 4 accounts:
1. @Pathik_Trader
2. @sourabhsiso19
3. @ITRADE191
4. @DillikiBiili
Share for the benefit of everyone.
Here are the setups from @Pathik_Trader Sir first.
1. Open Drive (Intraday Setup explained)
#OpenDrive#intradaySetup
— Pathik (@Pathik_Trader) April 16, 2019
Sharing one high probability trending setup for intraday.
Few conditions needs to be met
1. Opening should be above/below previous day high/low for buy/sell setup.
2. Open=low (for buy)
Open=high (for sell)
(1/n)
Bactesting results of Open Drive
Already explained strategy of #opendrive
— Pathik (@Pathik_Trader) May 27, 2020
Backtested results in 30 stocks and nifty, banknifty.
Success ratio : approx 40-45%
RR average 1:2
Entry as per strategy
Stoploss = Open level
Exit 3:15 PM Or SL
39 months 14 months -ve, 25 +ve
Yearly all 4 years +ve performance. pic.twitter.com/nGqhzMKGVy
2. Two Price Action setups to get good long side trade for intraday.
1. PDC Acts as Support
2. PDH Acts as
So today we will discuss two more price action setups to get good long side trade for intraday.
— Pathik (@Pathik_Trader) June 20, 2020
1. PDC Acts as Support
2. PDH Acts as Support
Example of PDC/PDH Setup given
#nifty
— Pathik (@Pathik_Trader) June 23, 2020
This is how it created long setup by taking support at PDC.
hopefully shared setup on last weekend helped. pic.twitter.com/2mduSUpMn5


#ஆதித்தியஹ்ருதயம் ஸ்தோத்திரம்
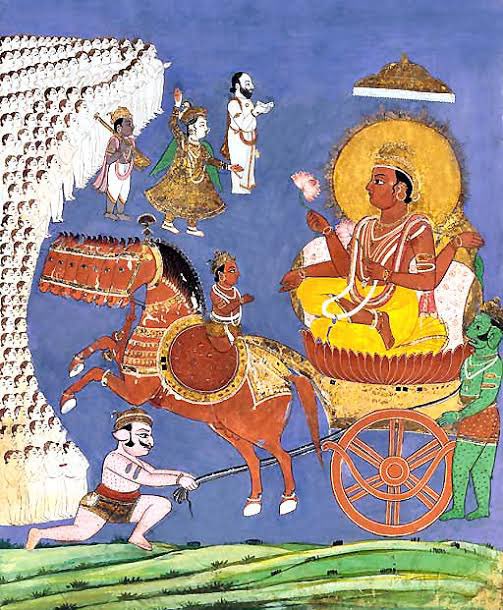
இது சூரிய குலத்தில் உதித்த இராமபிரானுக்கு தமிழ் முனிவர் அகத்தியர் உபதேசித்ததாக வால்மீகி இராமாயணத்தில் வருகிறது. ஆதித்ய ஹ்ருதயத்தைத் தினமும் ஓதினால் பெரும் பயன் பெறலாம் என மகான்களும் ஞானிகளும் காலம் காலமாகக் கூறி வருகின்றனர். ராம-ராவண யுத்தத்தை
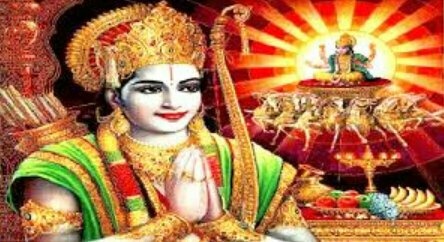
தேவர்களுடன் சேர்ந்து பார்க்க வந்திருந்த அகத்தியர், அப்போது போரினால் களைத்து, கவலையுடன் காணப்பட்ட ராமபிரானை அணுகி, மனிதர்களிலேயே சிறந்தவனான ராமா போரில் எந்த மந்திரத்தைப் பாராயணம் செய்தால் எல்லா பகைவர்களையும் வெல்ல முடியுமோ அந்த ரகசிய மந்திரத்தை, வேதத்தில் சொல்லப்பட்டுள்ளதை உனக்கு
நான் உபதேசிக்கிறேன், கேள் என்று கூறி உபதேசித்தார். முதல் இரு சுலோகங்கள் சூழ்நிலையை விவரிக்கின்றன. மூன்றாவது சுலோகம் அகத்தியர் இராமபிரானை விளித்துக் கூறுவதாக அமைந்திருக்கிறது. நான்காவது சுலோகம் முதல் முப்பதாம் சுலோகம் வரை ஆதித்ய ஹ்ருதயம் என்னும் நூல். முப்பத்தி ஒன்றாம் சுலோகம்
இந்தத் துதியால் மகிழ்ந்த சூரியன் இராமனை வாழ்த்துவதைக் கூறுவதாக அமைந்திருக்கிறது.
ஐந்தாவது ஸ்லோகம்:
ஸர்வ மங்கள் மாங்கல்யம் ஸர்வ பாப ப்ரநாசனம்
சிந்தா சோக ப்ரசமனம் ஆயுர் வர்த்தனம் உத்தமம்
பொருள்: இந்த அதித்ய ஹ்ருதயம் என்ற துதி மங்களங்களில் சிறந்தது, பாவங்களையும் கவலைகளையும்
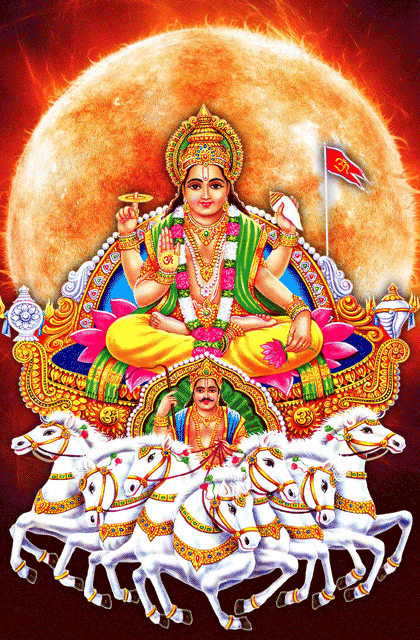
குழப்பங்களையும் நீக்குவது, வாழ்நாளை நீட்டிப்பது, மிகவும் சிறந்தது. இதயத்தில் வசிக்கும் பகவானுடைய அனுக்ரகத்தை அளிப்பதாகும்.
முழு ஸ்லோக லிங்க் பொருளுடன் இங்கே உள்ளது https://t.co/Q3qm1TfPmk
சூரியன் உலக இயக்கத்திற்கு மிக முக்கியமானவர். சூரிய சக்தியால்தான் ஜீவராசிகள், பயிர்கள்
இது சூரிய குலத்தில் உதித்த இராமபிரானுக்கு தமிழ் முனிவர் அகத்தியர் உபதேசித்ததாக வால்மீகி இராமாயணத்தில் வருகிறது. ஆதித்ய ஹ்ருதயத்தைத் தினமும் ஓதினால் பெரும் பயன் பெறலாம் என மகான்களும் ஞானிகளும் காலம் காலமாகக் கூறி வருகின்றனர். ராம-ராவண யுத்தத்தை
தேவர்களுடன் சேர்ந்து பார்க்க வந்திருந்த அகத்தியர், அப்போது போரினால் களைத்து, கவலையுடன் காணப்பட்ட ராமபிரானை அணுகி, மனிதர்களிலேயே சிறந்தவனான ராமா போரில் எந்த மந்திரத்தைப் பாராயணம் செய்தால் எல்லா பகைவர்களையும் வெல்ல முடியுமோ அந்த ரகசிய மந்திரத்தை, வேதத்தில் சொல்லப்பட்டுள்ளதை உனக்கு
நான் உபதேசிக்கிறேன், கேள் என்று கூறி உபதேசித்தார். முதல் இரு சுலோகங்கள் சூழ்நிலையை விவரிக்கின்றன. மூன்றாவது சுலோகம் அகத்தியர் இராமபிரானை விளித்துக் கூறுவதாக அமைந்திருக்கிறது. நான்காவது சுலோகம் முதல் முப்பதாம் சுலோகம் வரை ஆதித்ய ஹ்ருதயம் என்னும் நூல். முப்பத்தி ஒன்றாம் சுலோகம்
இந்தத் துதியால் மகிழ்ந்த சூரியன் இராமனை வாழ்த்துவதைக் கூறுவதாக அமைந்திருக்கிறது.
ஐந்தாவது ஸ்லோகம்:
ஸர்வ மங்கள் மாங்கல்யம் ஸர்வ பாப ப்ரநாசனம்
சிந்தா சோக ப்ரசமனம் ஆயுர் வர்த்தனம் உத்தமம்
பொருள்: இந்த அதித்ய ஹ்ருதயம் என்ற துதி மங்களங்களில் சிறந்தது, பாவங்களையும் கவலைகளையும்
குழப்பங்களையும் நீக்குவது, வாழ்நாளை நீட்டிப்பது, மிகவும் சிறந்தது. இதயத்தில் வசிக்கும் பகவானுடைய அனுக்ரகத்தை அளிப்பதாகும்.
முழு ஸ்லோக லிங்க் பொருளுடன் இங்கே உள்ளது https://t.co/Q3qm1TfPmk
சூரியன் உலக இயக்கத்திற்கு மிக முக்கியமானவர். சூரிய சக்தியால்தான் ஜீவராசிகள், பயிர்கள்