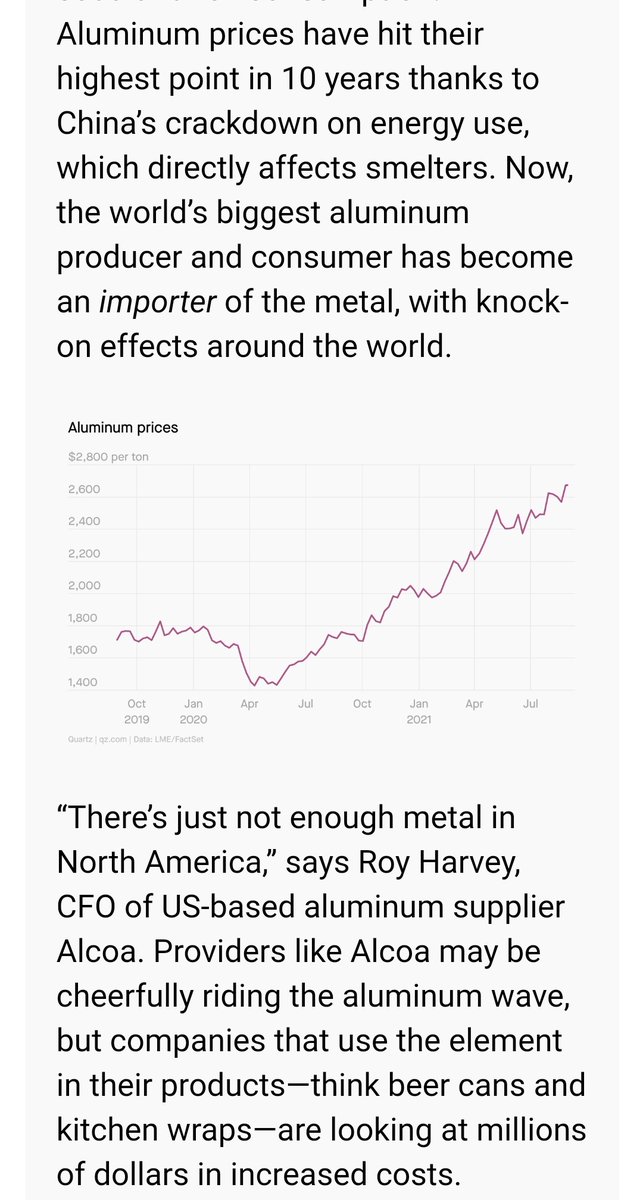
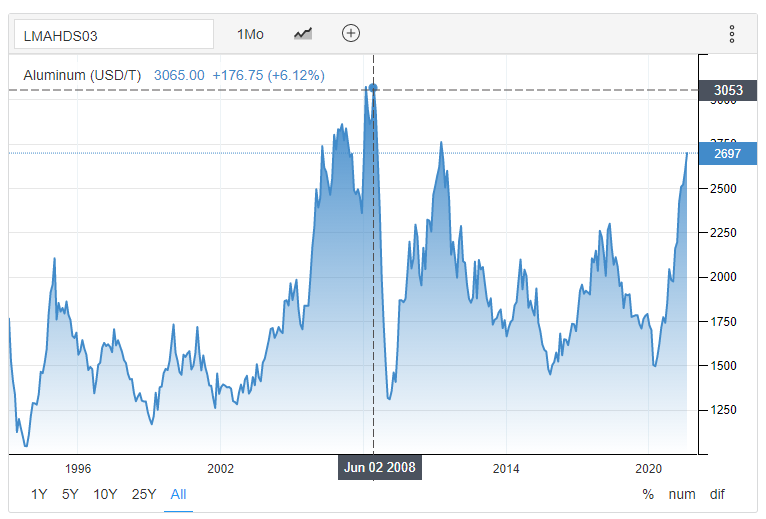
Aluminum prices have risen almost 40% this year on the LME. https://t.co/yWD0I1yECY pic.twitter.com/IhaJD53mmX
— Lisa Abramowicz (@lisaabramowicz1) August 31, 2021
China becomes a net importer of Aluminium
Crackdown on factories in China driven by political rulings to curb emissions
Nalco delivers the highest grossing quarter ever
2+2 = 20 https://t.co/paEk76EaGT
Common theme coming out of China is
— Tar \u26a1 (@itsTarH) August 31, 2021
1\u20e3 Govt wants to focus on general prosperity than just prosperity of a few
2\u20e3 Large focus on limiting emissions
3\u20e3 Willing to lose market share and global dominance in some categories to achieve the above
Bodes well for some sectors in India.
https://t.co/aqbthw1gFP

More from Tar ⚡

Open Question to fellow investors tracking Music Industry.
A business like Universal which controls more than 1/3rd of all published music globally is selling for less than 6x FY20 Sales.
Why are Indian businesses like Saregama / Tips selling for 11x, 20x their sales?
If I include all of the revenue generated by entire firm, its selling for ~4.5x FY20 Sales
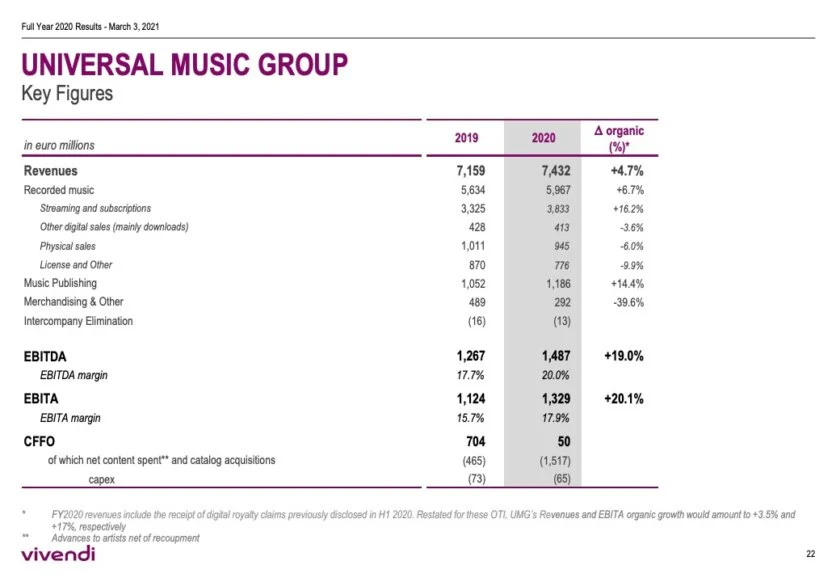
Universal Listing Market Cap ~ 40 Billion USD
FY 20 Revenues ~ 8.87 B USD or 7.4B EUR
Catalogue of Music includes every international artist you can possibly name
Either Universal is grossly undervalued or Saregama/Tips are grossly overvalued.
https://t.co/aHzWSYtcUt
https://t.co/v0EMoCuYKX
A business like Universal which controls more than 1/3rd of all published music globally is selling for less than 6x FY20 Sales.
Why are Indian businesses like Saregama / Tips selling for 11x, 20x their sales?
If I include all of the revenue generated by entire firm, its selling for ~4.5x FY20 Sales
Universal Listing Market Cap ~ 40 Billion USD
FY 20 Revenues ~ 8.87 B USD or 7.4B EUR
Catalogue of Music includes every international artist you can possibly name
Either Universal is grossly undervalued or Saregama/Tips are grossly overvalued.
https://t.co/aHzWSYtcUt
Homework for all the interested participants here:
— Intrinsic Compounding (@soicfinance) June 27, 2021
Q1.Why 20% and not 50%+ Margins for UMG
Q2. Differences in dynamics between Western&Indian cos?
Q3. Trends in West vs Trends in India in the industry.
Research and find the answers. My job is done \U0001f601\U0001f64f
https://t.co/v0EMoCuYKX
If you see the ebitda of universal music its low 20% compared to our saregama 30% or tips 50%. So when you compare earnings saregama is 40x and tips is 30x and universal music is 30x. Also these type of companies are less( low or no capex with excellent and growinh cashflows)
— Srikanth V (@mynameisnani75) June 27, 2021

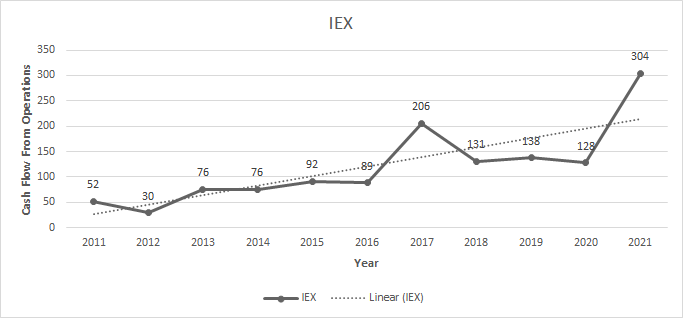
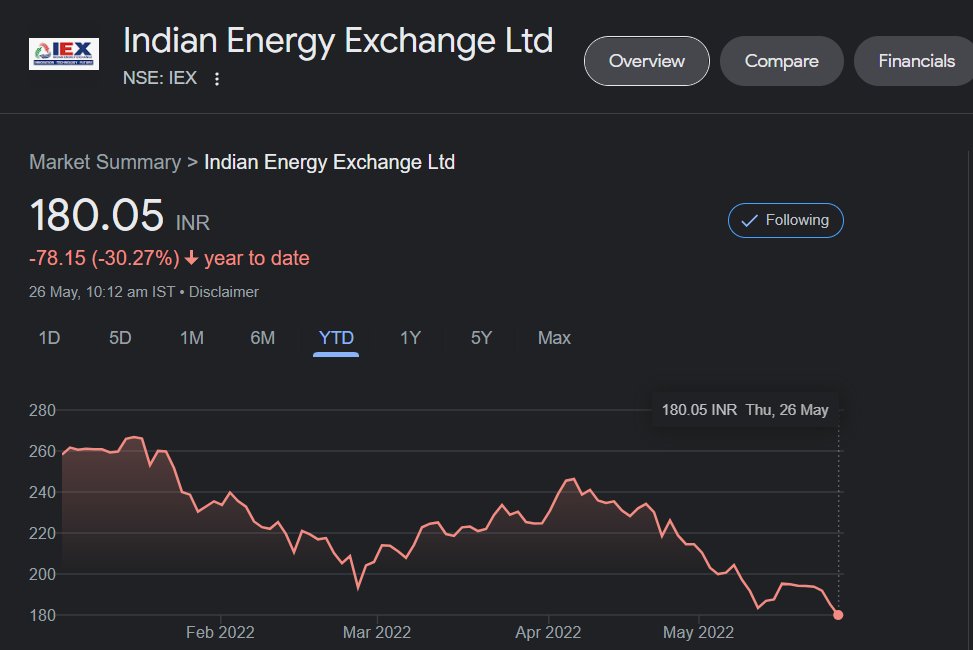
#IEX finally getting close to my average price, will start adding it below 150 (15% further correction from here)
Please do your due diligence and do not copy me blindly here
My investments in IEX are part of an experiment to hold a good stock for 10 yrs + buying sporadically
IEX has also started ground work for trading carbon credits
Still believe this is one stock where dividend every year in 10 years can be equal to my entire investment amount considering it throws up so much cash
Still maintain
NSE + Zerodha =
Please do your due diligence and do not copy me blindly here
My investments in IEX are part of an experiment to hold a good stock for 10 yrs + buying sporadically
IEX has also started ground work for trading carbon credits
Still believe this is one stock where dividend every year in 10 years can be equal to my entire investment amount considering it throws up so much cash
Still maintain
NSE + Zerodha =
#IEX in my PF is a giant growing dividend paying Gorilla
— Tar \u26a1 (@itsTarH) October 18, 2021
Main reason I don't mess around with my holdings is cause I expect it to.
Pay Dividend = to my investment within the next decade
Glad they are considering Bonus Issue (tax favorable) instead of Cash Dividend. pic.twitter.com/2cLt6yK0Xw